30 minutes · 1:1 on Zoom · ₹9 back if you learn nothing new
FinProRealtorsEMI × 12 × Tenure₹9 back if nothing newVinod, 1:1
🏠 30 Minutes · 1:1 on Zoom · For salaried professionals &
business owners with a ₹50 lakh to ₹2 crore home loan
In 30 Minutes, See Exactly WhatYour Home Loan Will Cost You Over 20 YearsAnd The Framework Built To Push That NumberTowards Zero. Or Your ₹9 Back.
"Zero Interest" does not mean the bank charges you nothing. It means
we structure your loan and your surplus so that what your money
earns offsets what your loan costs - so your net interest moves
towards zero. The bank still charges. Your money starts working
against that charge.
▶
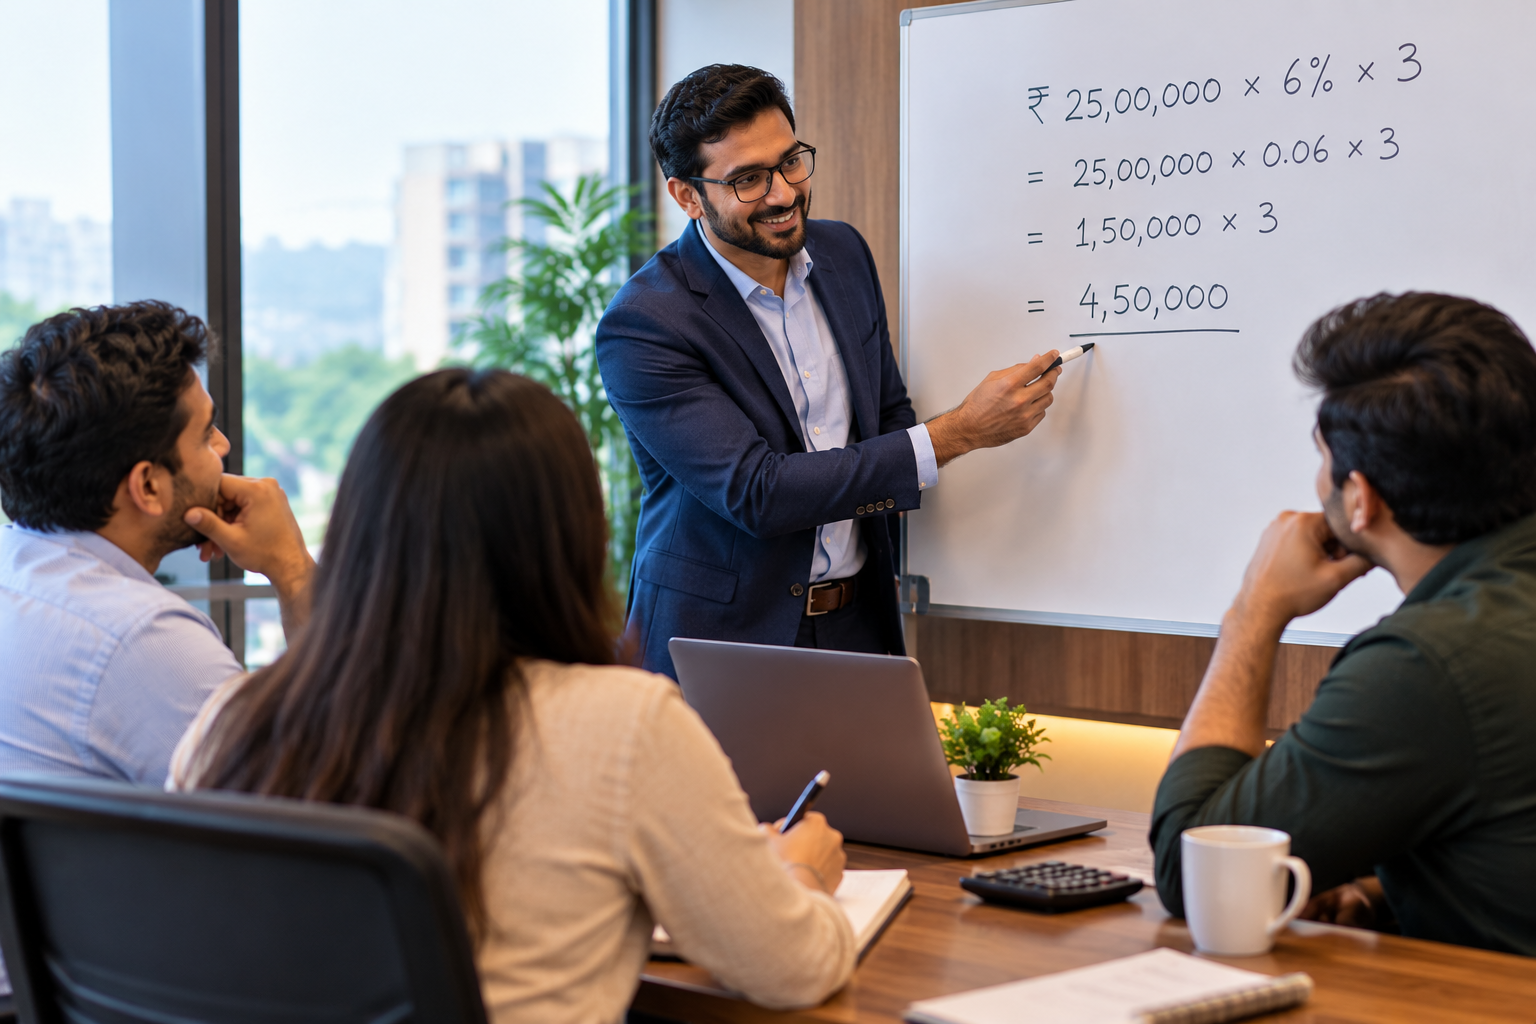
45-second VSL - Vinod, direct to camera: "Open your calculator.
Your EMI, times twelve, times your tenure. Now subtract the loan
amount. Most people have never once seen that number, and it is
bigger than the house."
You have spent three months choosing between two flats. You spent
about six minutes choosing the loan - and the loan is the one that
will cost you more.
This Session Is For One Specific Person.
Read Both Lists Before You Book.
✓ This is you
You are 28 to 45, salaried or running your own business, and
you are buying a home between ₹50 lakh and ₹2 crore
The loan will be ₹40 lakh to ₹1.5 crore, over 20 or 25 years,
and the EMI will take 35 to 45 percent of your take-home
You have the money and the eligibility. What you do not have
is one person who can tell you whether this is the right
decision
A builder, a broker, a bank and an uncle on WhatsApp have each
given you different advice, and all four of them are selling
something
You built an Excel sheet. It made the confusion worse, not
better
And there is one sentence you have not said out loud to
anybody: "What if this turns out to be wrong?"
✗ This is not you
You want a bank that charges zero interest. No bank does, this
session will say so in the first two minutes, and anybody who
tells you otherwise is lying to you
You want a guaranteed saving figure. You will not be given one
here, ever. You will be given arithmetic instead
You have already signed and the loan has disbursed. Come
anyway if you like, but far less is moveable after signature
than before
You want someone to confirm the decision you have already
made. You may be told the numbers do not work
If you are in the first list, thirty minutes from now you will know
the real twenty-year cost of the biggest financial decision of your
life, and whether the EMI is safe against your income. If you
are in the second, please do not book. Vinod takes every one of
these sessions himself and there are only ten to twelve a week.
10 to 12 sessions a week · Vinod takes every one himself
You Are Not Confused Because You Are Careless. You Are Confused
Because Nobody Has Shown You The Number.
Forty seconds. Do this before you read another line. It needs
nothing but your phone.
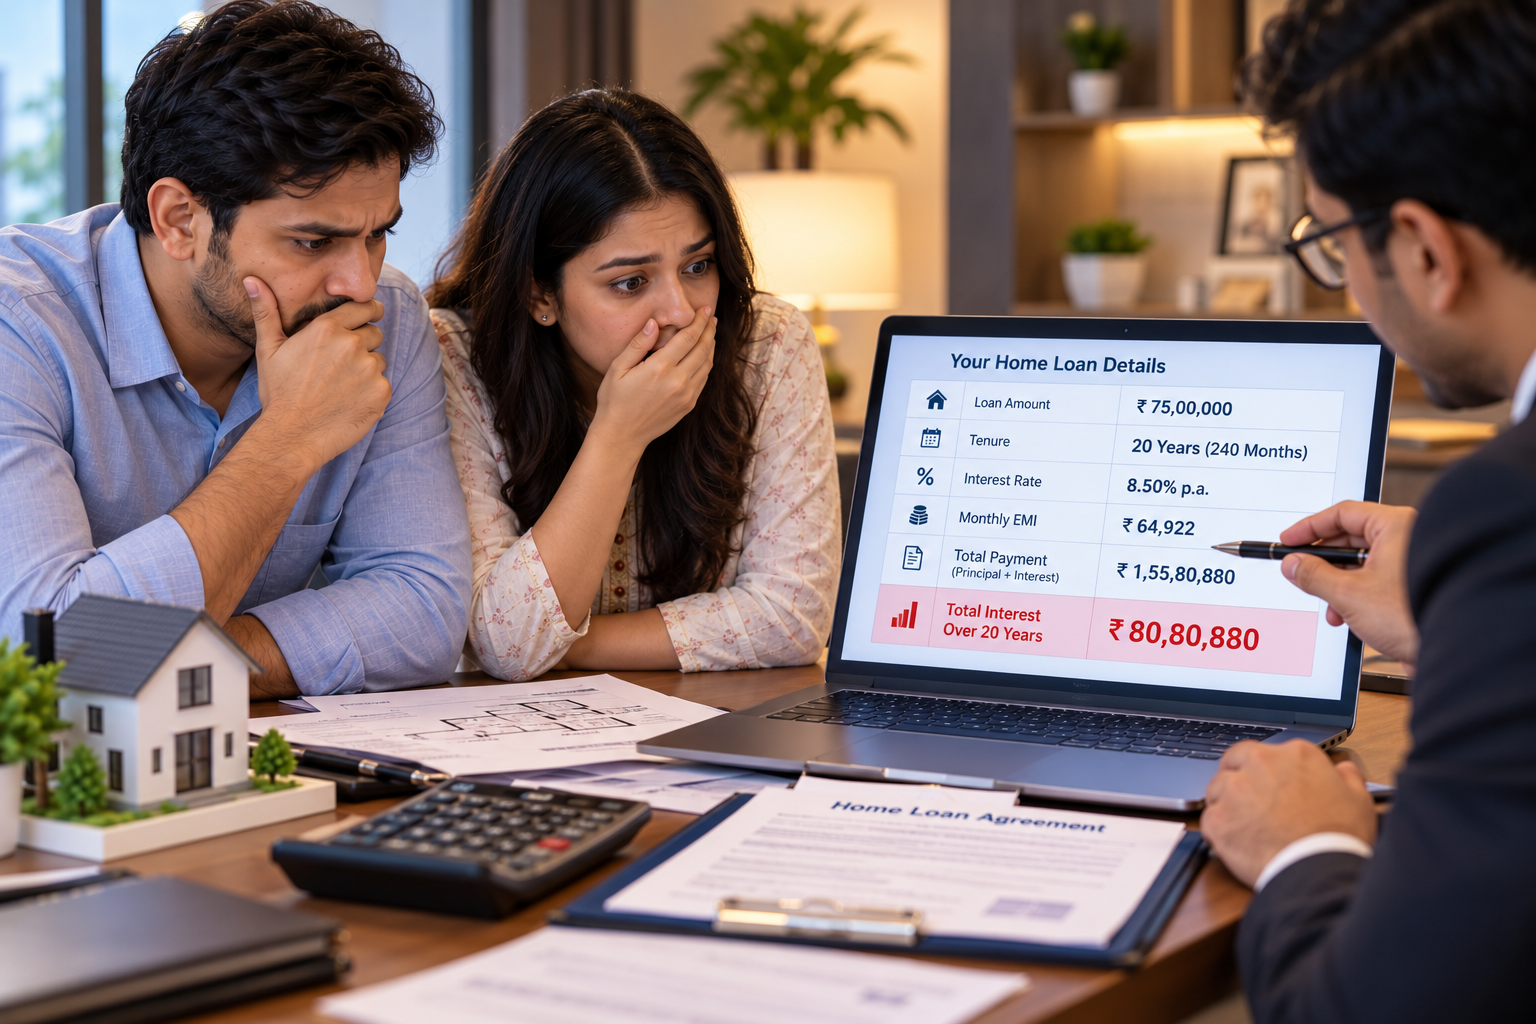
Open your calculator. Take your EMI. Multiply it by 12. Multiply
that by your tenure in years. Now subtract the loan amount.
What is left is the interest. The real one, over the full tenure.
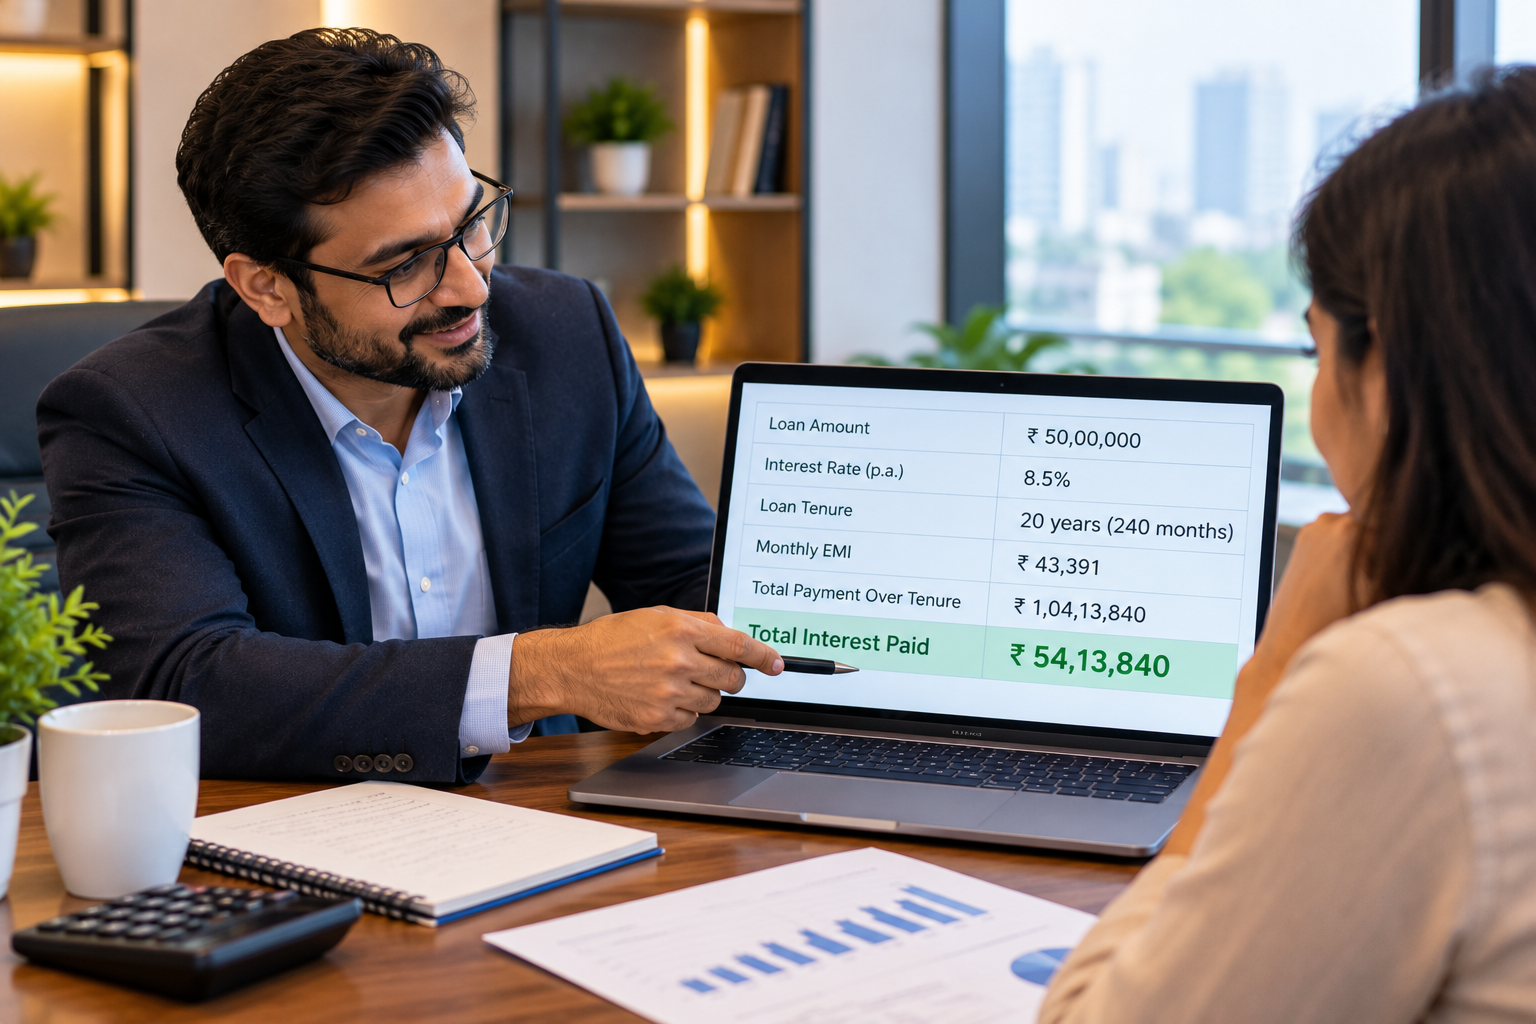
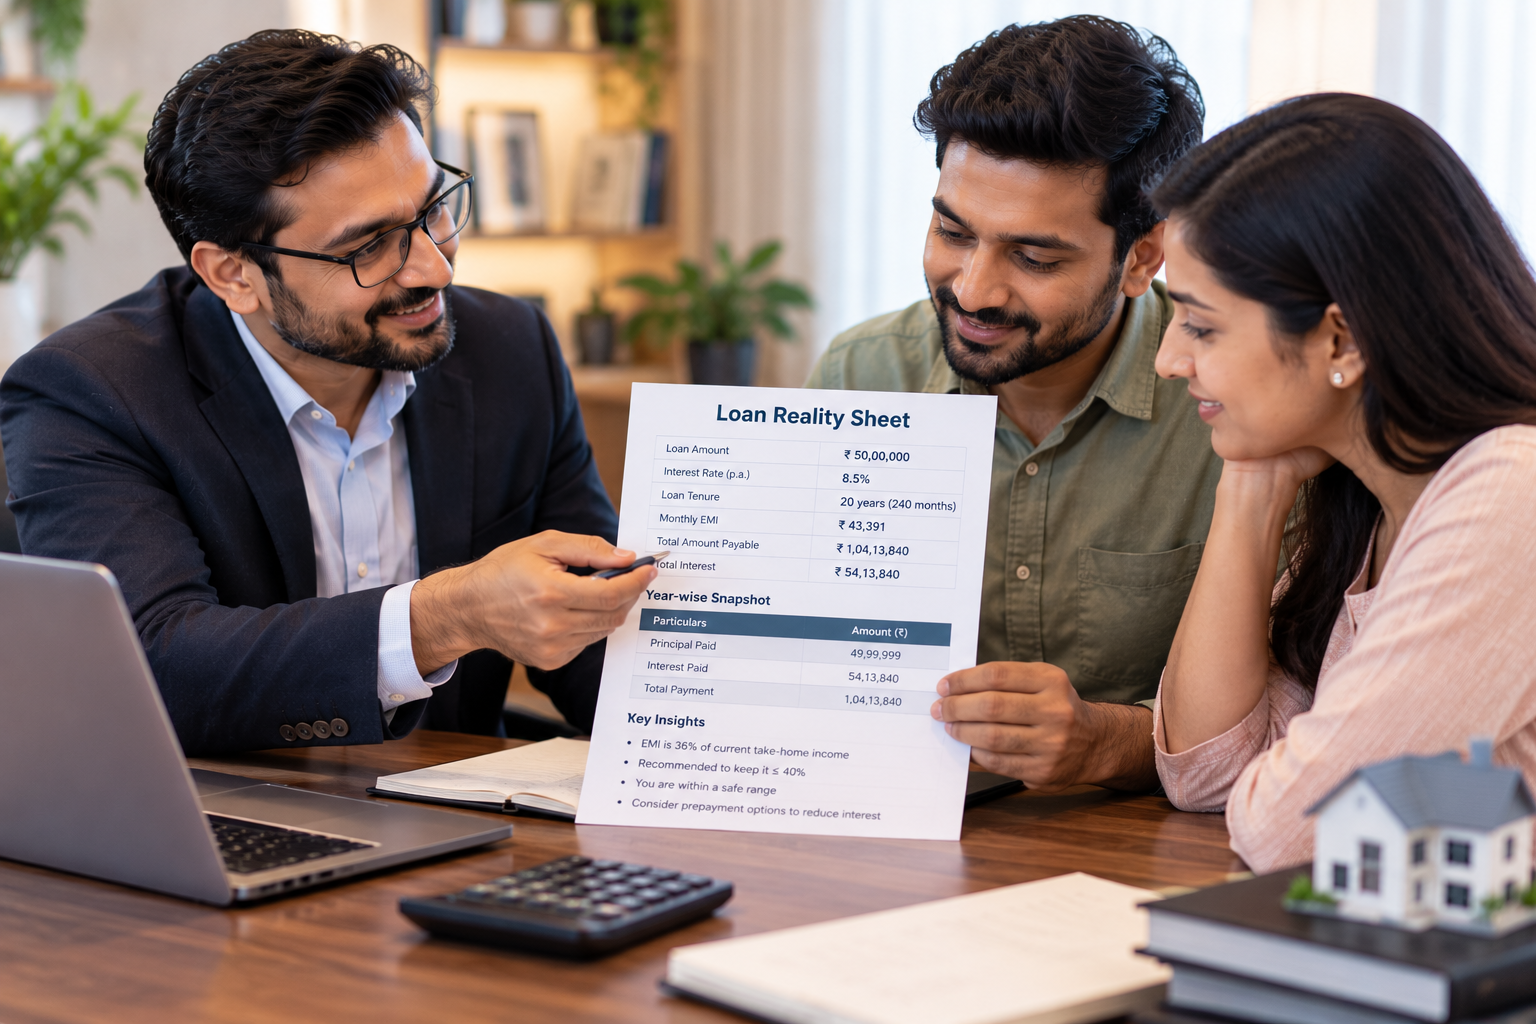
Here is what it looks like at an illustrative 8.5 percent:
LoanEMIInterest
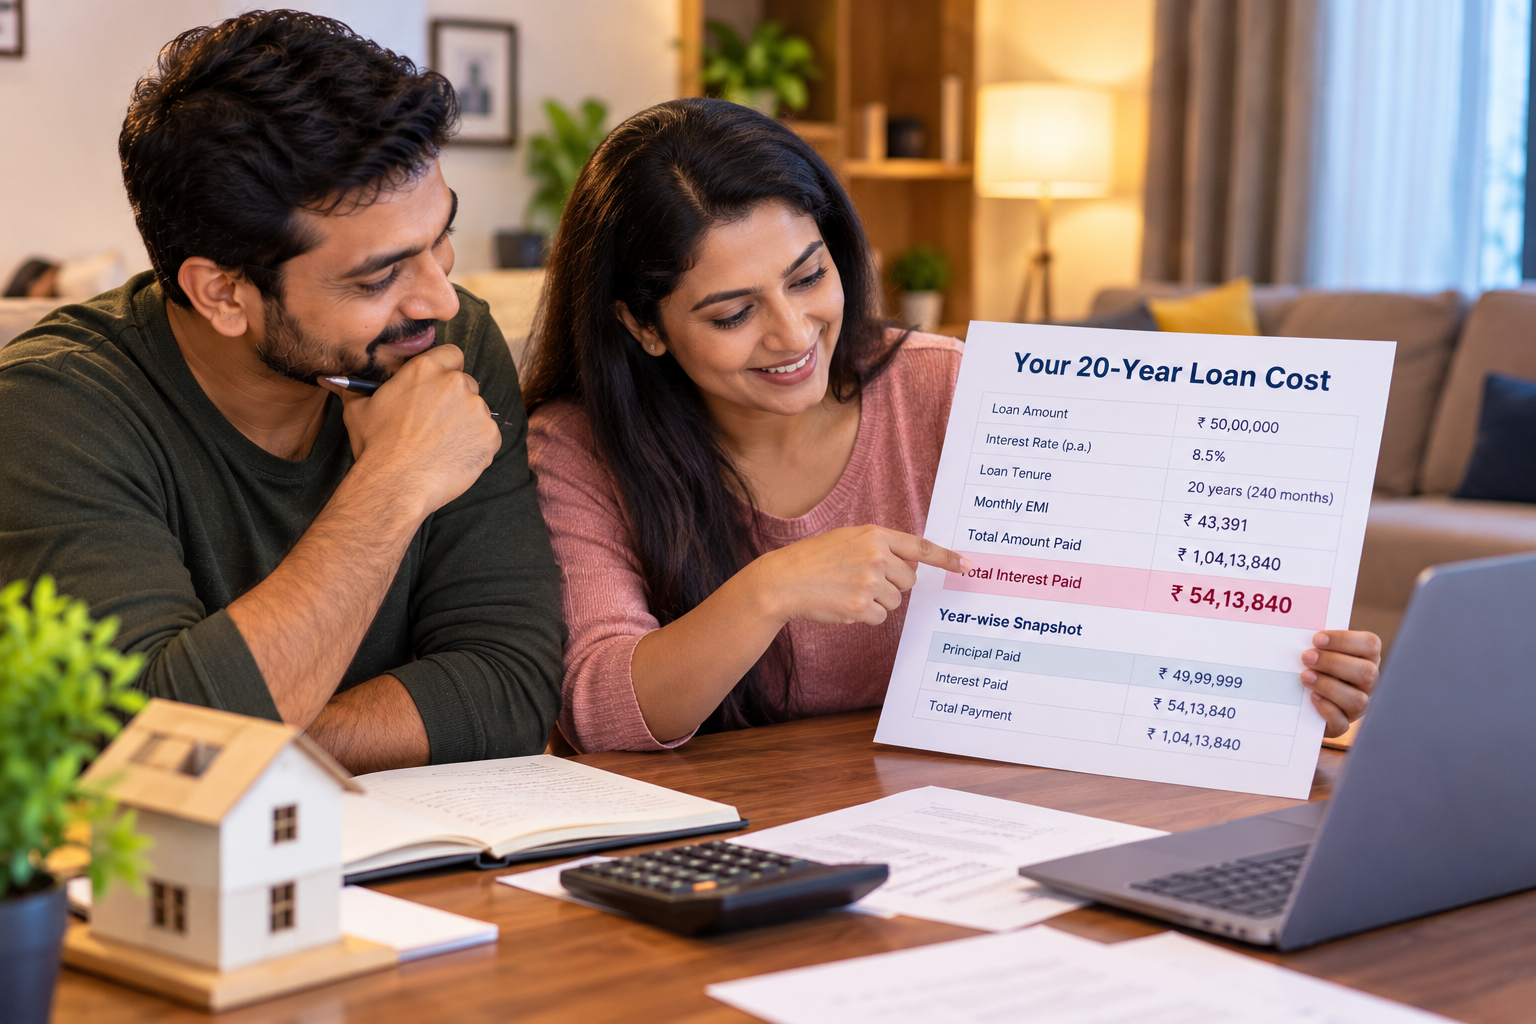
₹50 lakh · 20 yrs₹43,391₹54.1 lakh
₹50 lakh · 25 yrs₹40,261₹70.8 lakh
₹75 lakh · 20 yrs₹65,087₹81.2 lakh
₹1 crore · 20 yrs₹86,782₹1.08 crore
₹1 crore · 25 yrs₹80,523₹1.42 crore
Illustrative only, at 8.5%. Actual rate, tenure and outcome depend
on your lender, product and profile.
Look at the second row and the last row. Five extra years of tenure
on a ₹50 lakh loan costs about ₹16.7 lakh in extra interest. On a ₹1
crore loan it is about ₹33 lakh. Nobody told you that, because the
five extra years make the EMI look smaller, and a smaller EMI is
what gets the file approved. This is not a claim and it is not a
promise. It is arithmetic, and you just did it yourself on your own
phone.
Now hold that number in your head and look at how the last three
months have actually gone.
You chose the flat for three months. You chose the loan in an
afternoon.
Two flats, compared endlessly. Floor plans, carpet area, the
view, the commute, your wife's opinion, your mother's opinion.
And the loan - the thing that costs more than the flat over
twenty years - was whichever bank gave the pre-approval first.
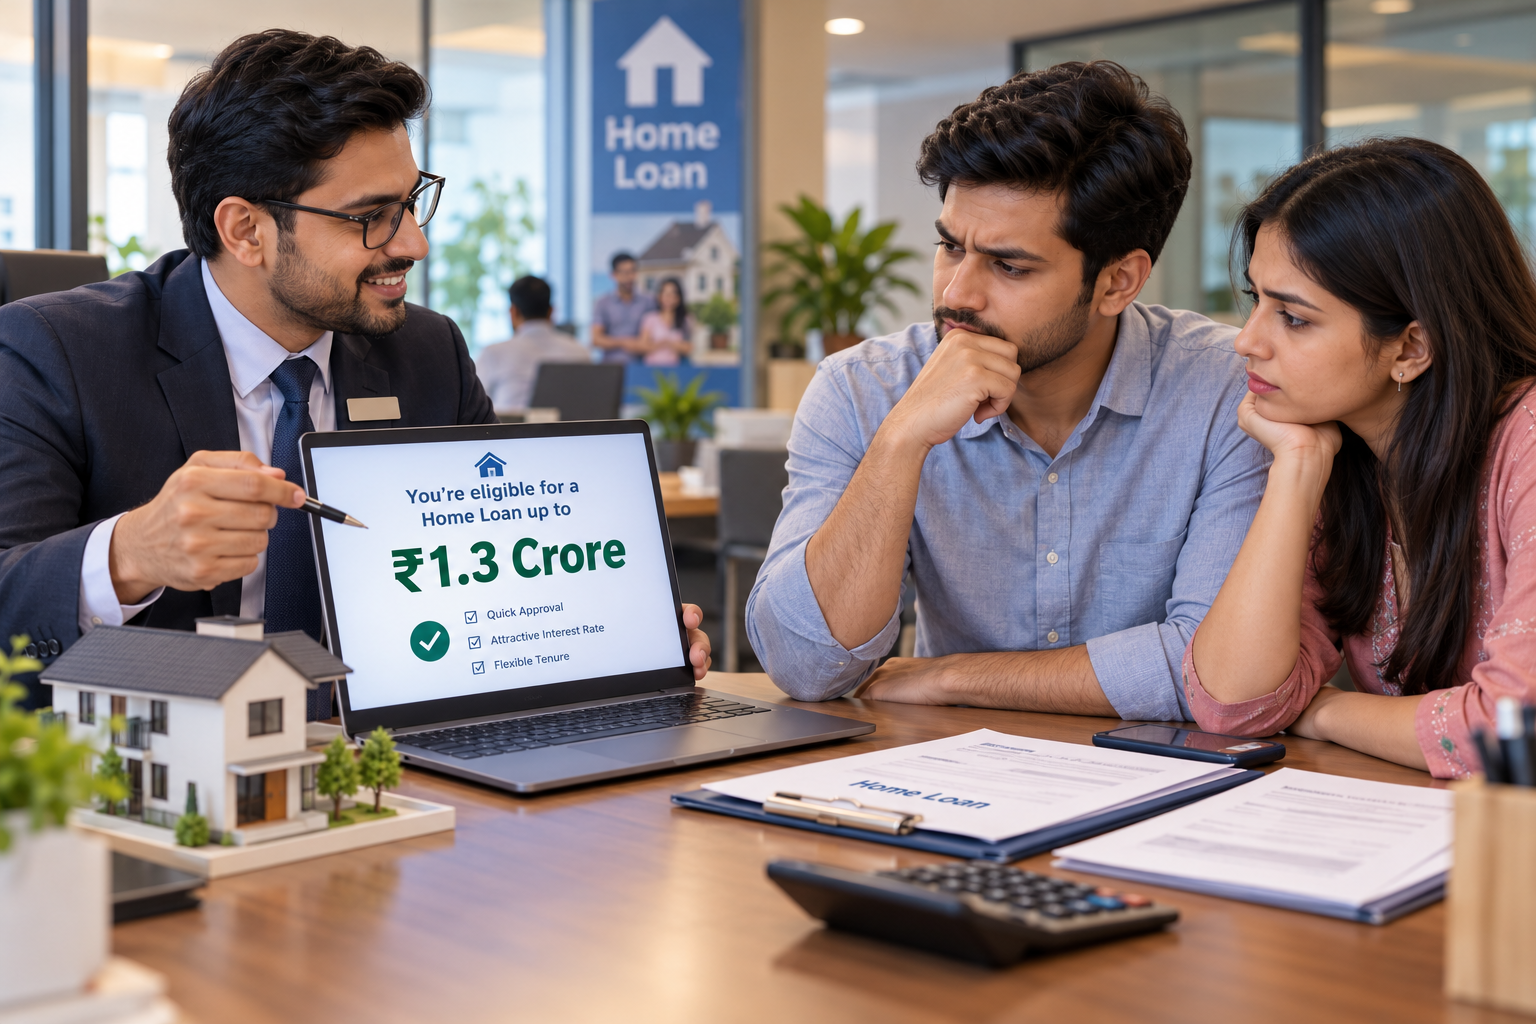
"Sir, you'll get up to ₹1.3 crore."
That is the only sentence a bank or a DSA is structurally able
to say to you. It is a statement about what you can borrow.
Not one person in this entire process has asked what you
should borrow. That is a completely different question and it
has a completely different answer.
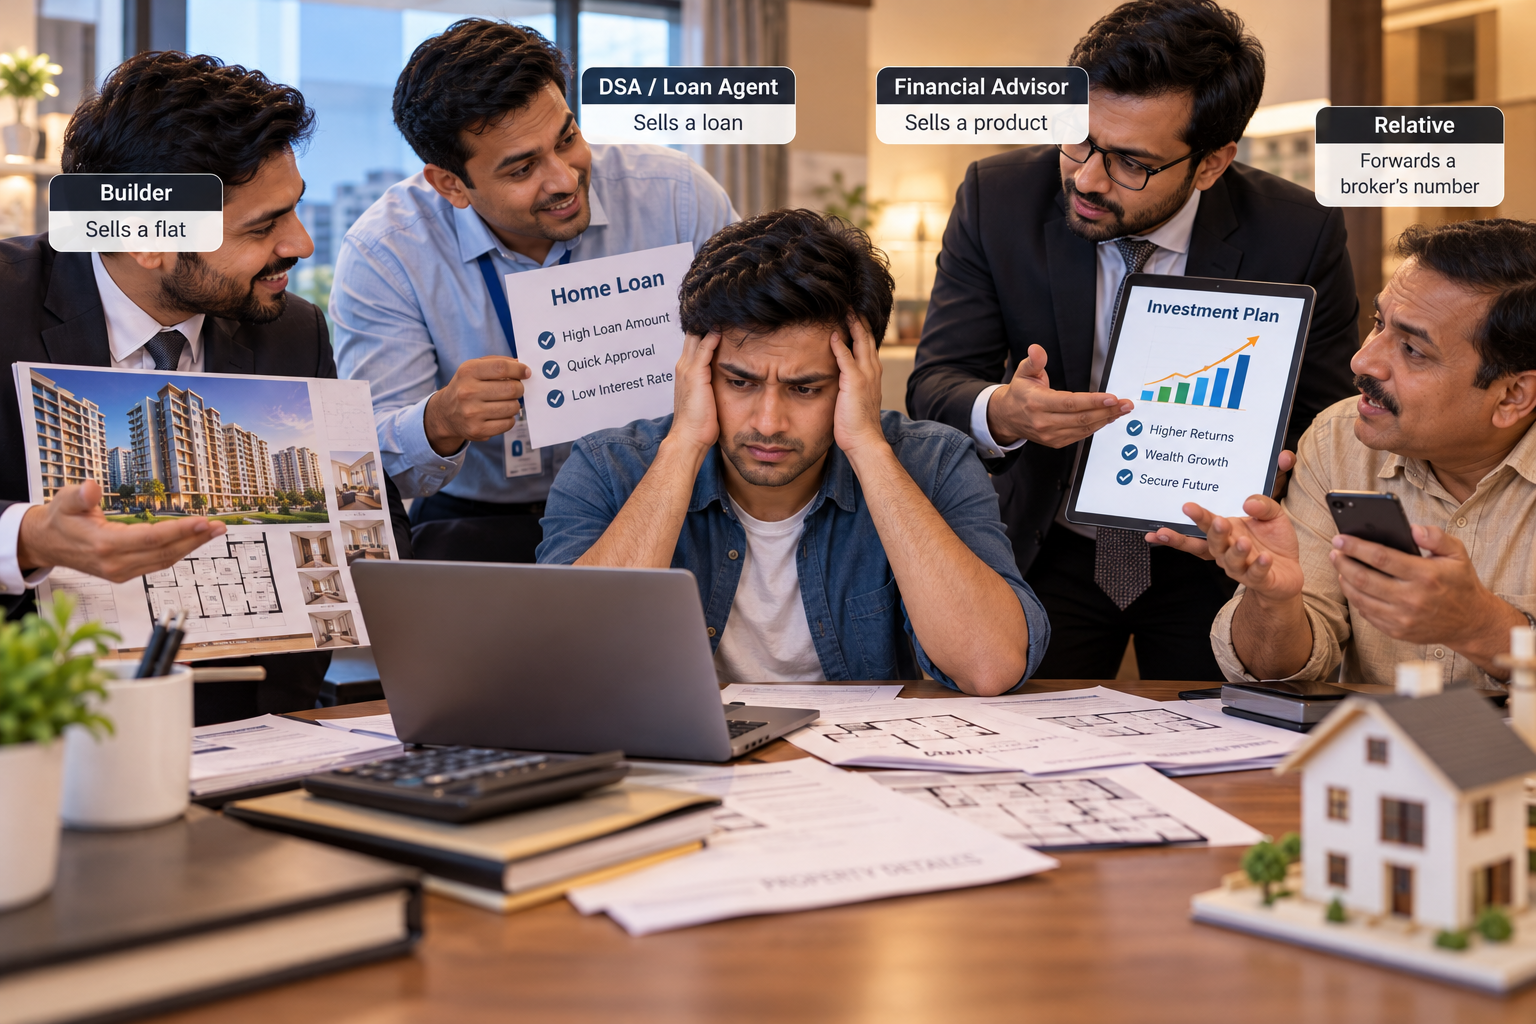
Four advisors. Four commissions. Zero people on your side.
The builder sells a flat. The DSA sells a loan. The advisor
sells a product. The relative forwards a broker's number. None
of them speak to each other, all of them get paid when you say
yes, and you are sitting in the middle trying to work out who
is telling the truth.
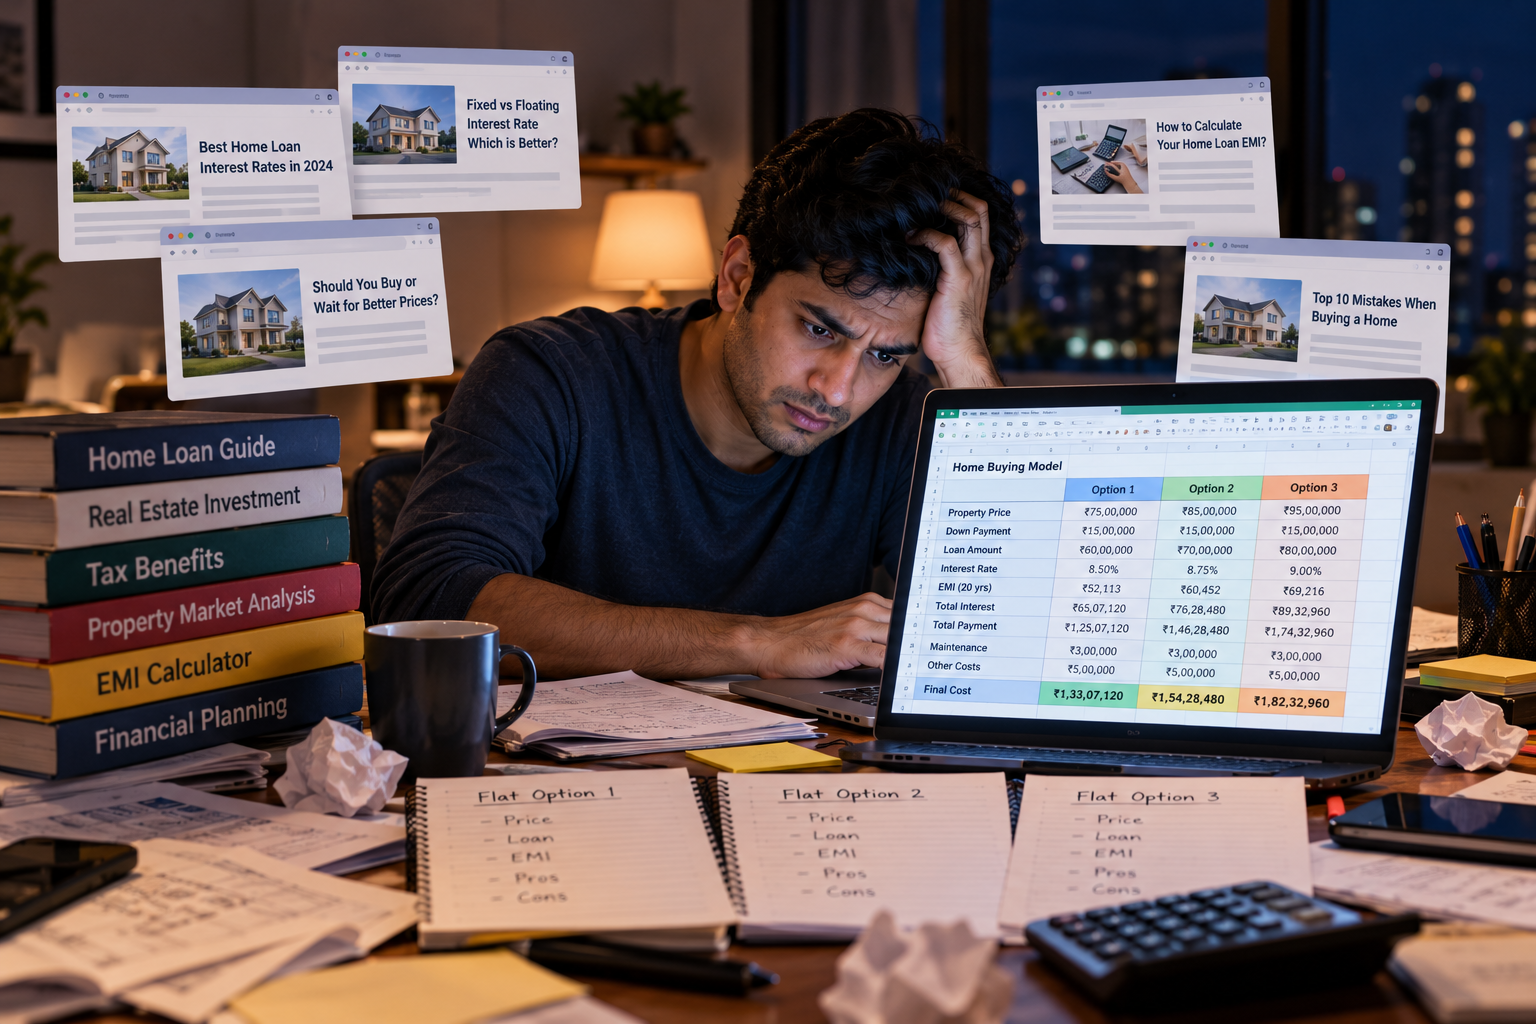
You built a model at eleven at night. It made things worse.
Because a spreadsheet gives you more numbers, and what you
were missing was never numbers. It was judgement. Information
is free and you have already read far too much of it. That is
part of the problem, not the cure.
You are an educated, capable person, so you do not ask basic
questions.
You are supposed to understand this. Everyone assumes you do.
So when a lender uses a term you do not know, you nod. And you
will sign a twenty-year commitment rather than look like the
one person in the room who did not follow.
Look at those five again and notice what is actually missing. Not
money. Not eligibility. Not intelligence - you built the
spreadsheet. Not effort - three months of site visits. What is
missing is one person who is paid by you, sitting on your side of
the table, who has no reason to care whether you buy.
The broker gets paid when you buy. The bank gets paid when you
borrow. Vinod gets paid when you decide - and sometimes that
decision is no.
30 Minutes, 1:1 On Zoom. Exactly What Happens In Them.
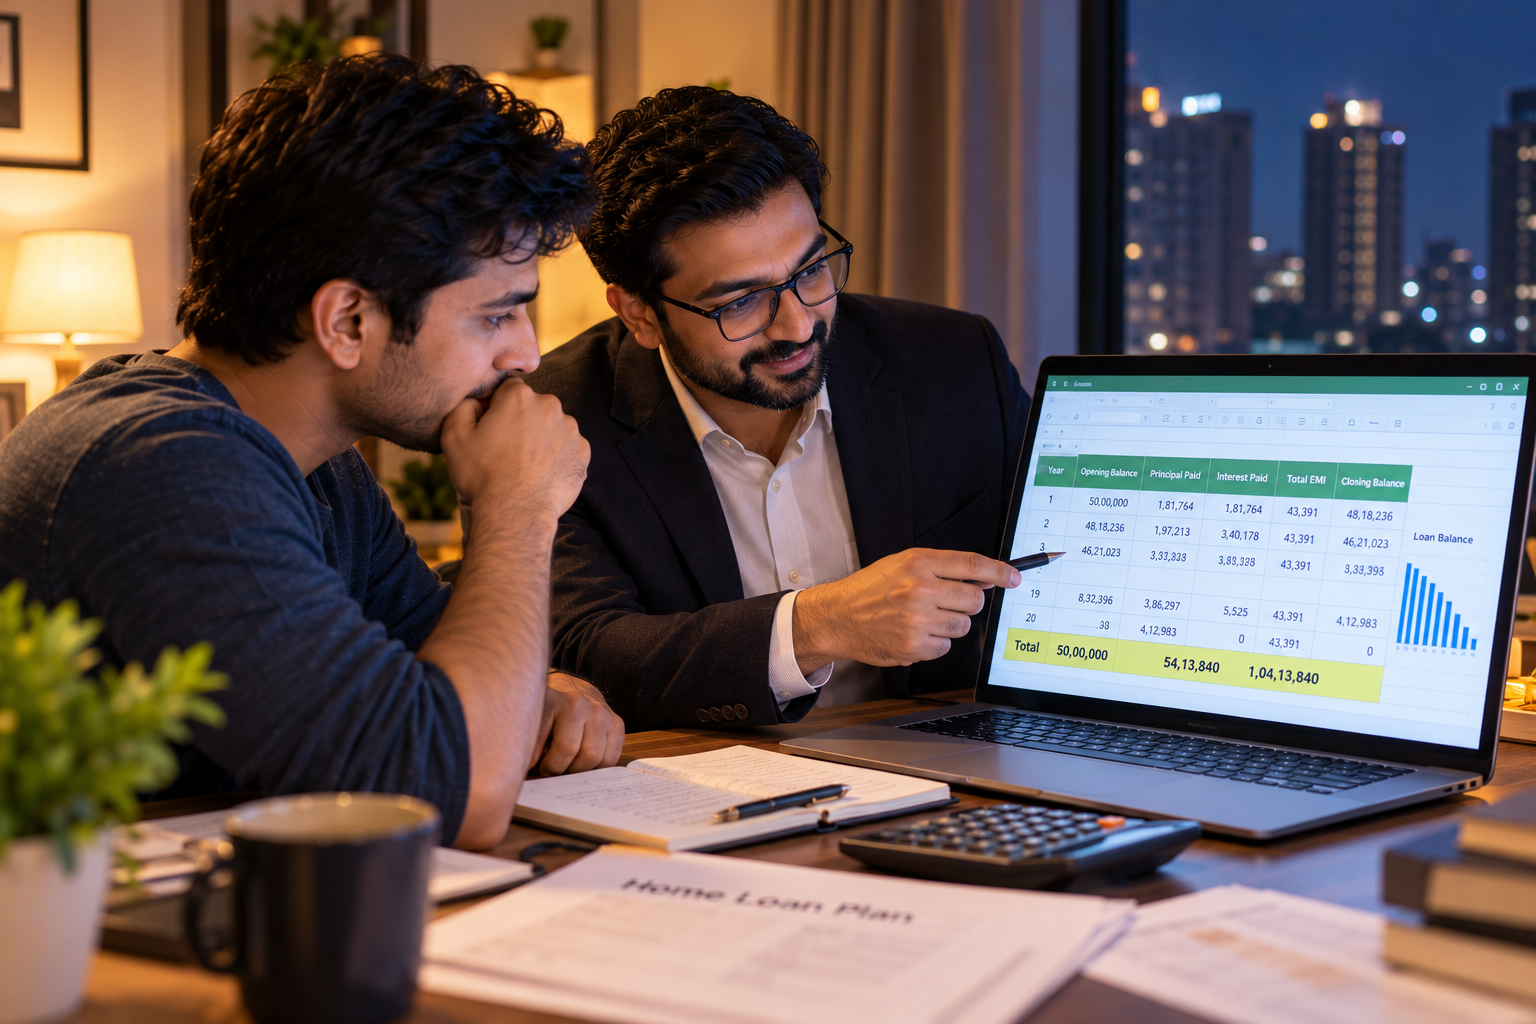
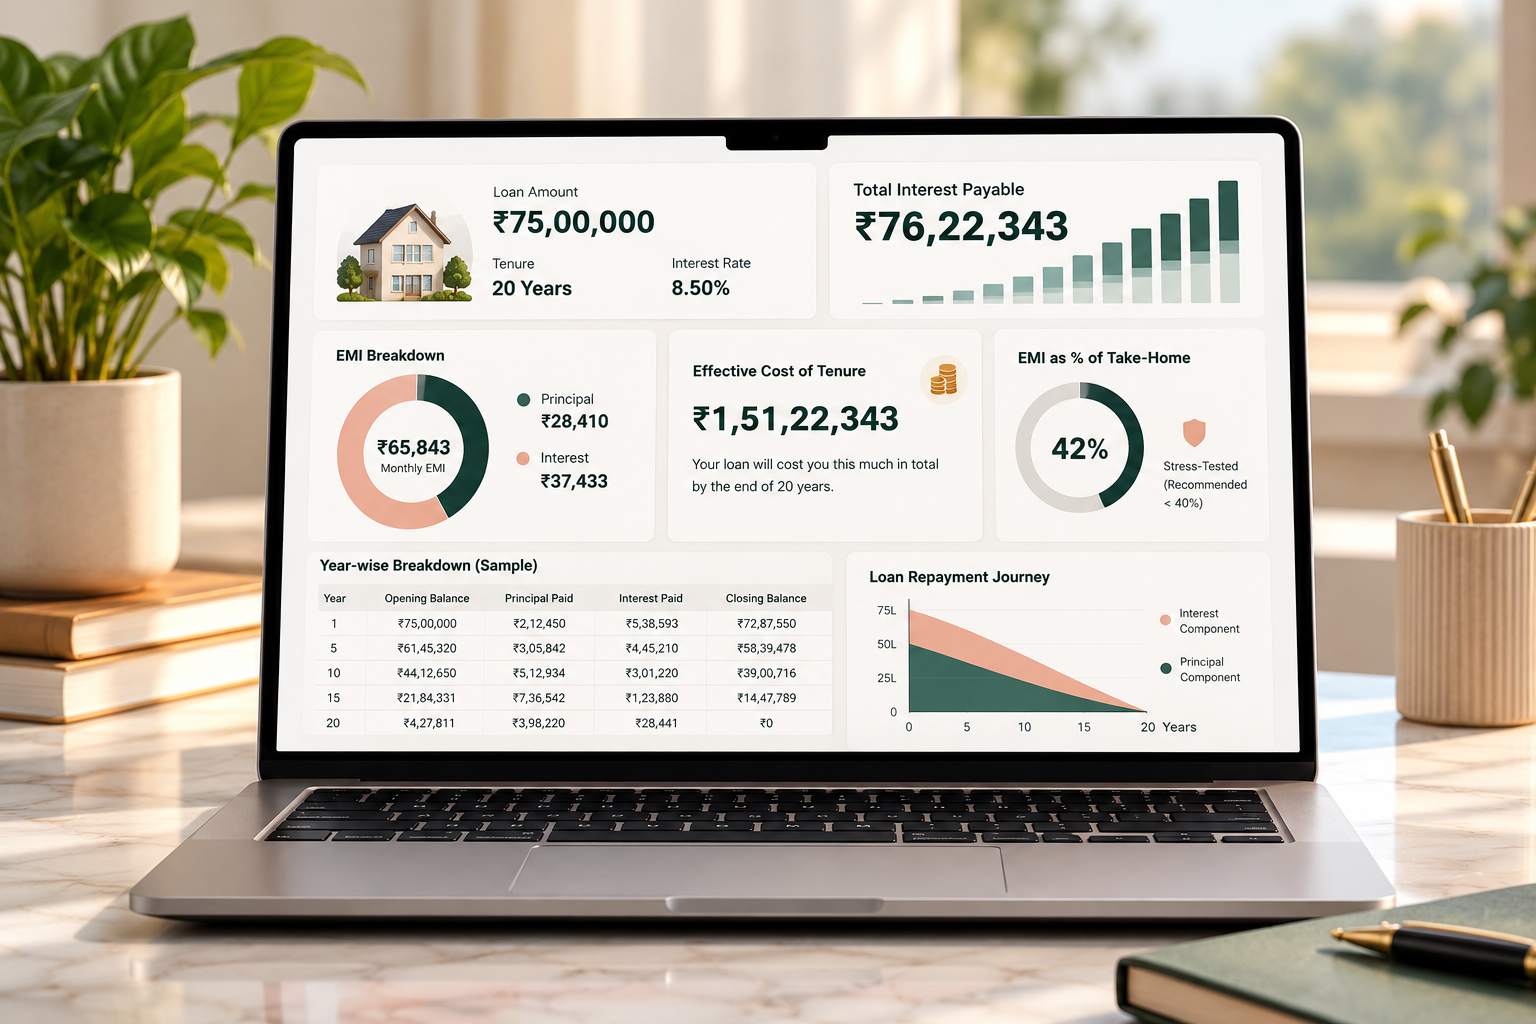
Your Real Number, on screen, in your own case
Not the illustration above. Yours. Your loan amount, your
tenure, your rate, your total interest over the full term.
Most people are seeing this for the first time in their life,
and most of them go quiet for a moment.
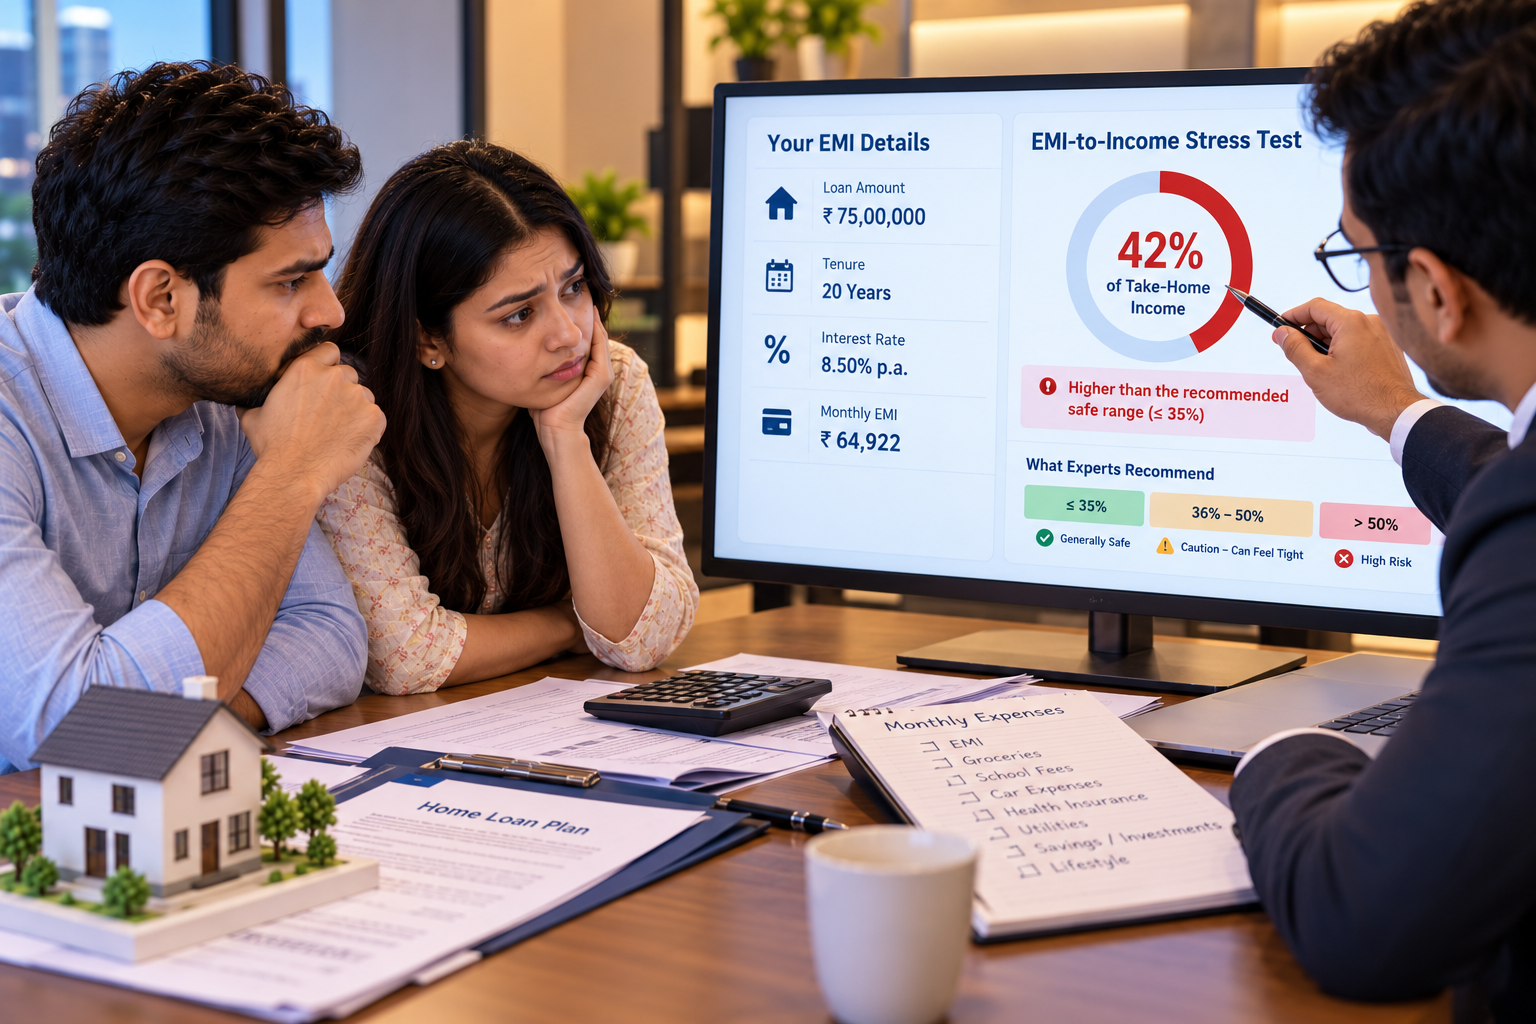
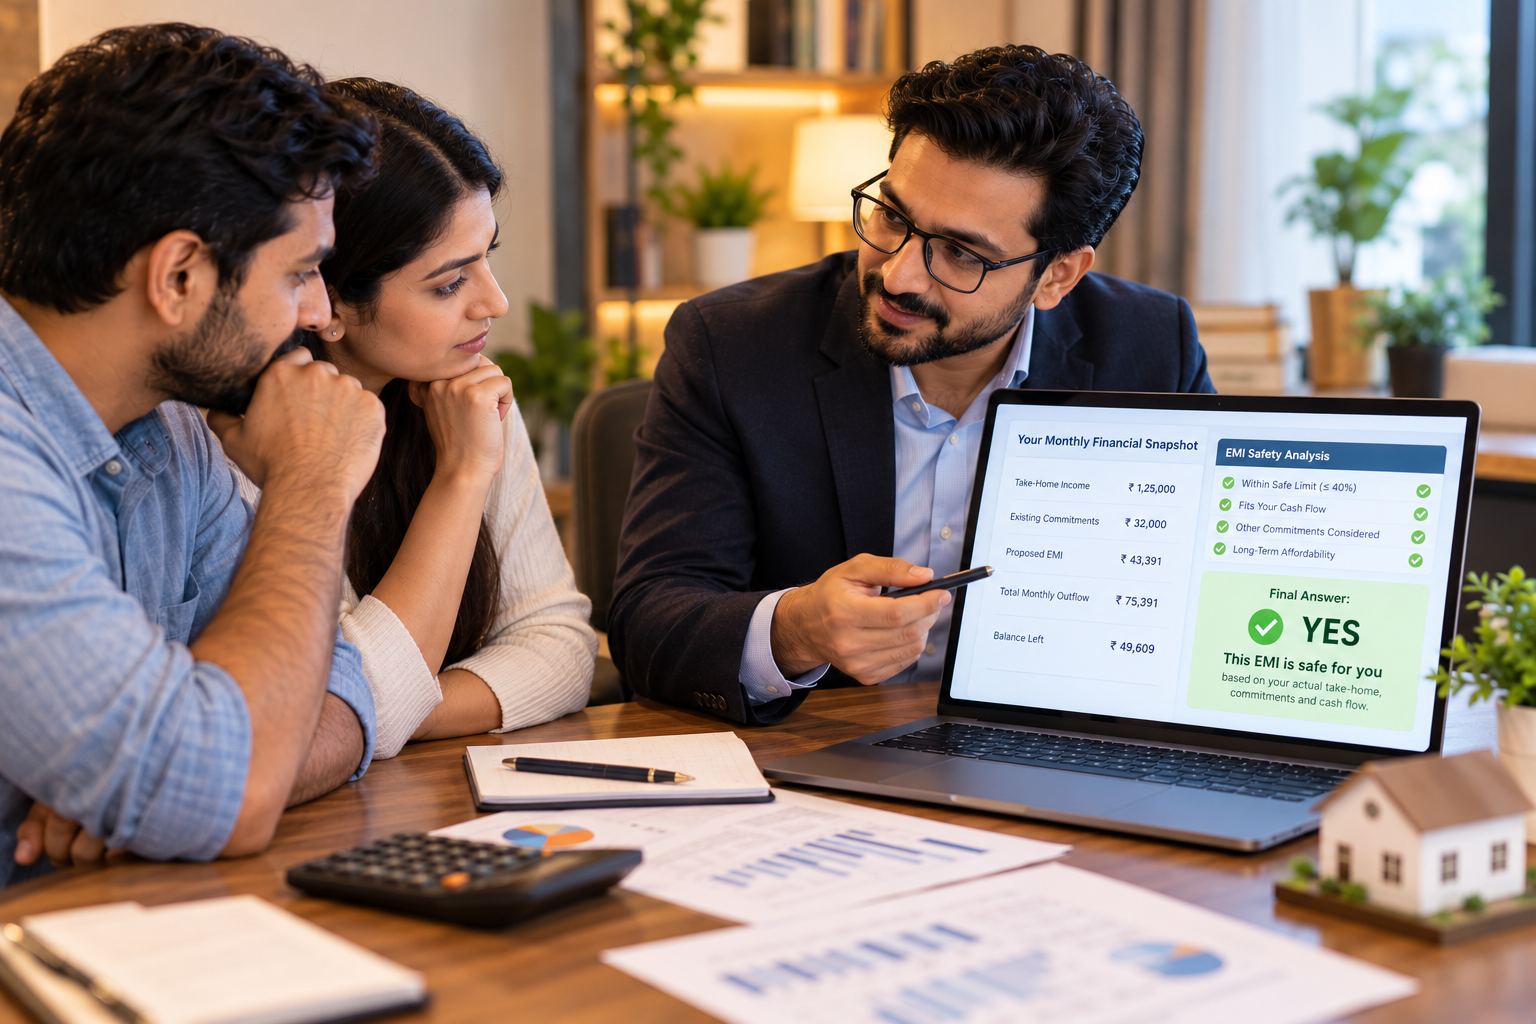
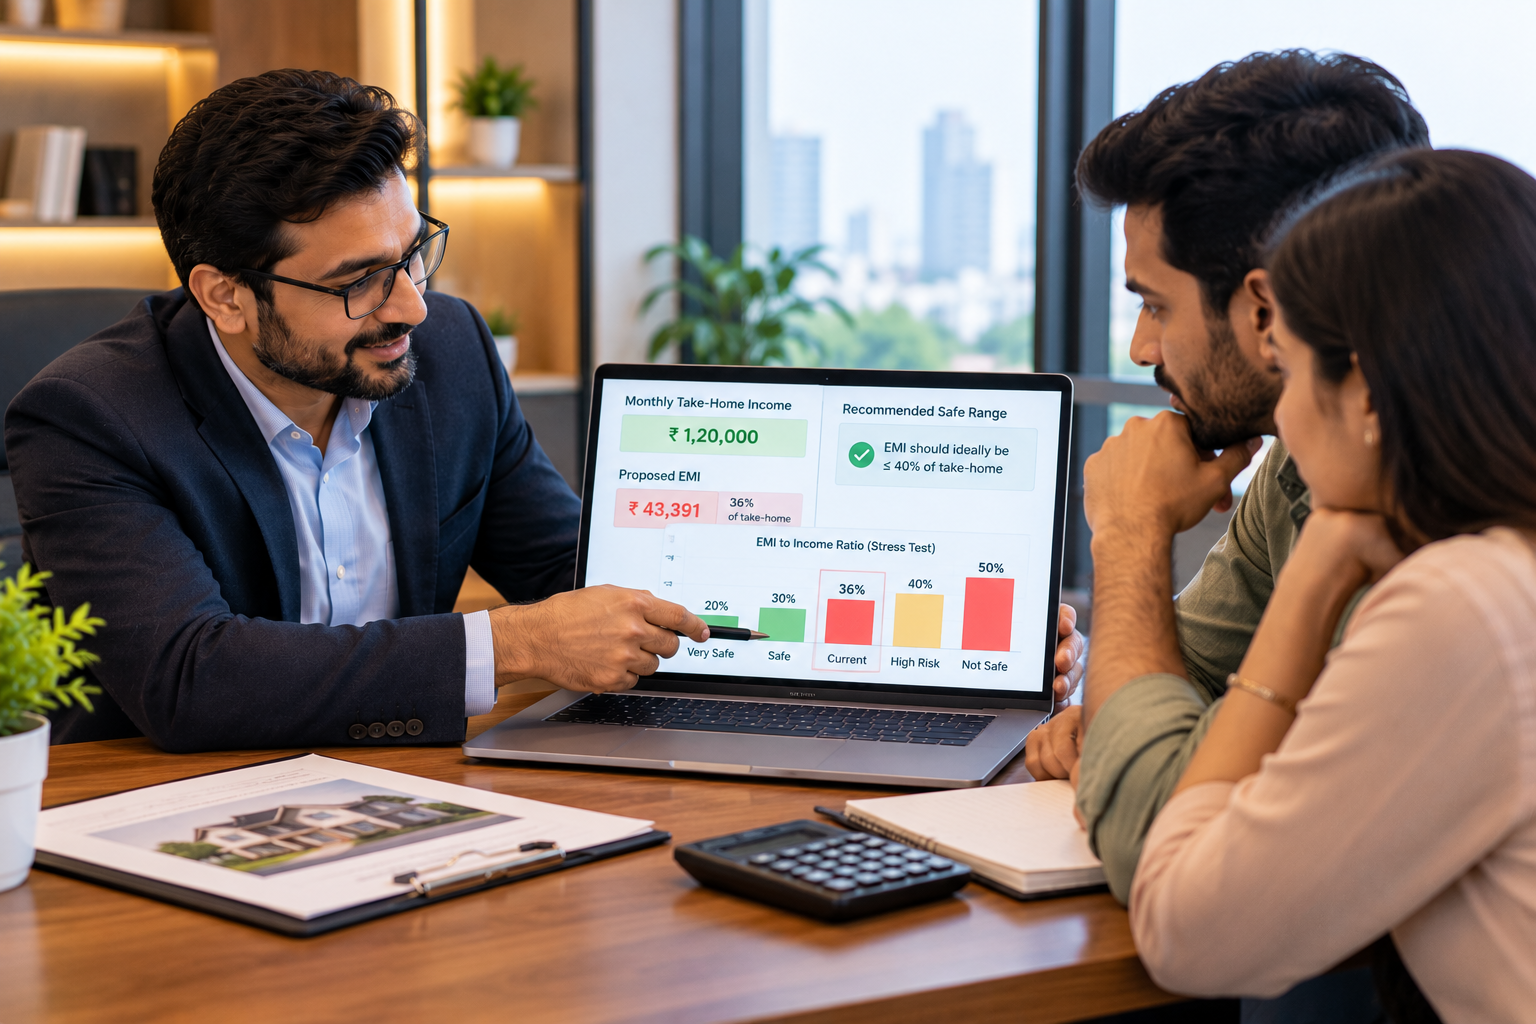
The EMI-to-income stress test
What percentage of your take-home that EMI actually eats, and
whether that number is safe for a twenty-year commitment or
whether it quietly makes every other decision in your life
smaller.
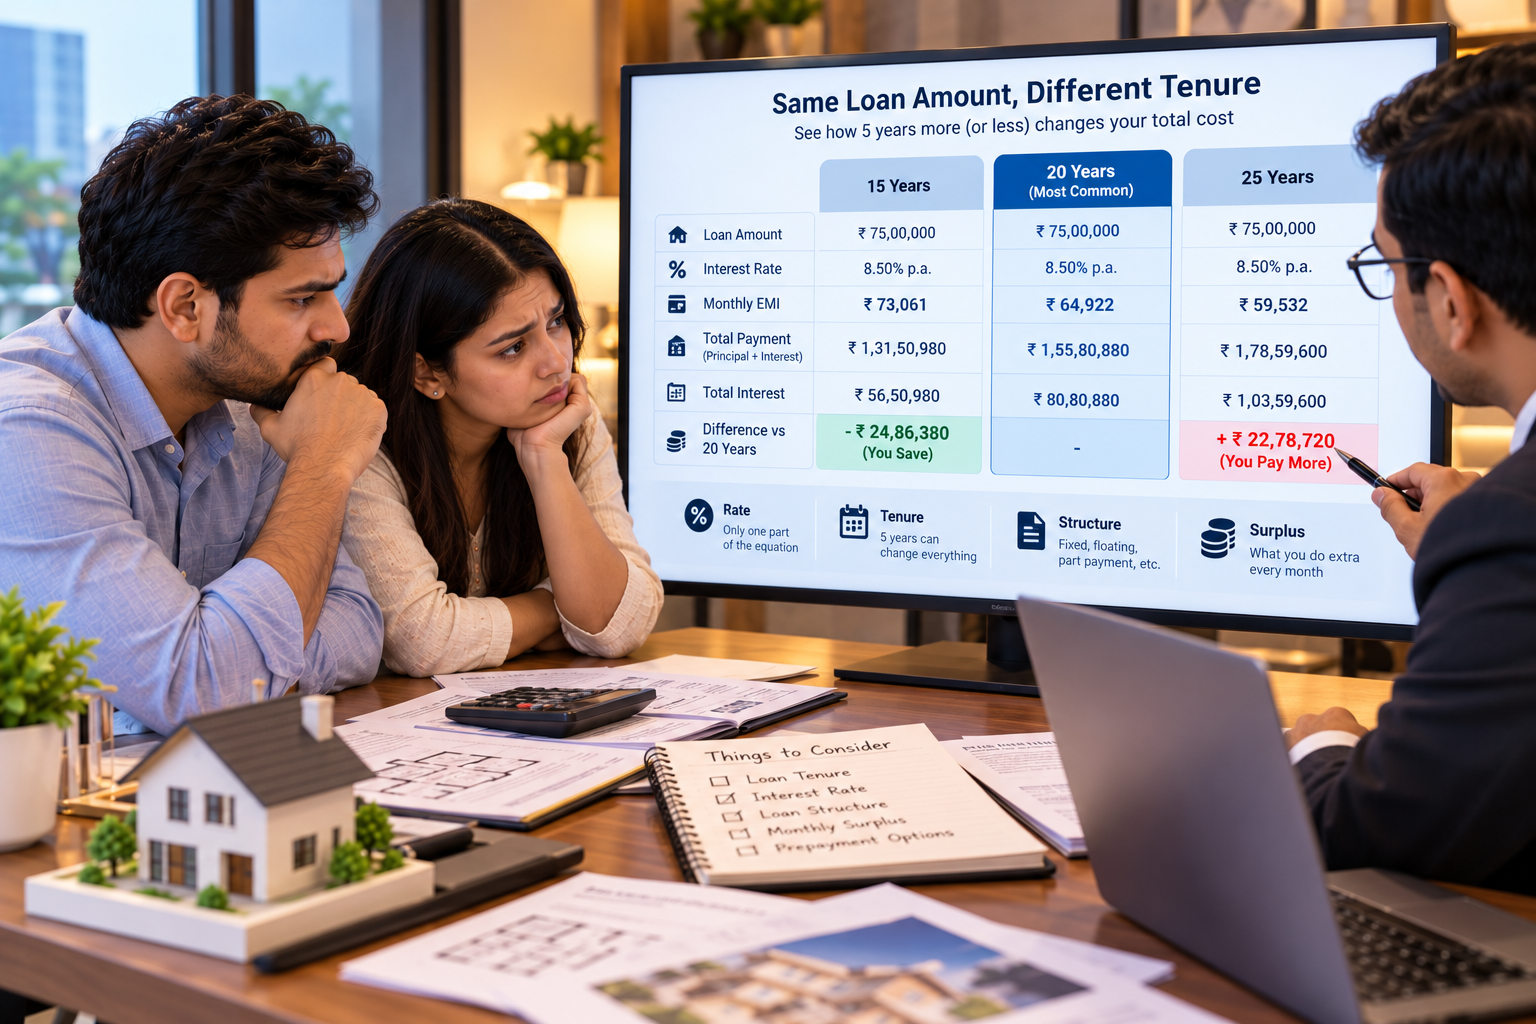
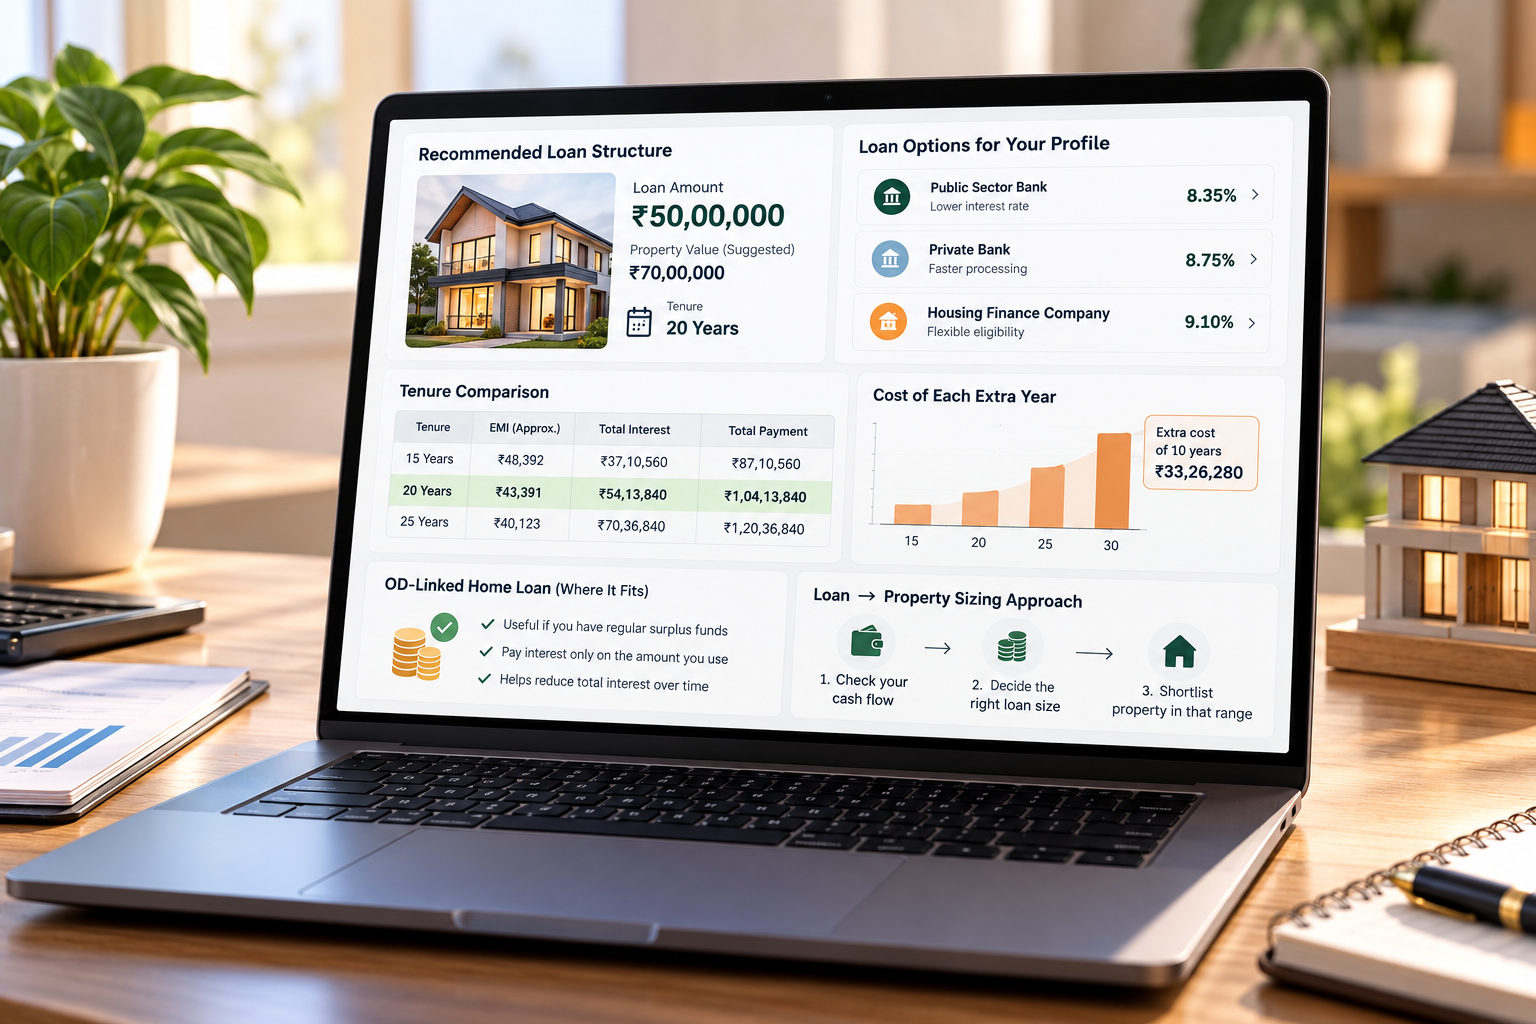
What five years of tenure is really costing you
Rate is one of four things that decide what a loan costs. The
other three are tenure, structure and what your surplus does
every month. Most people optimise the one and ignore the
three.
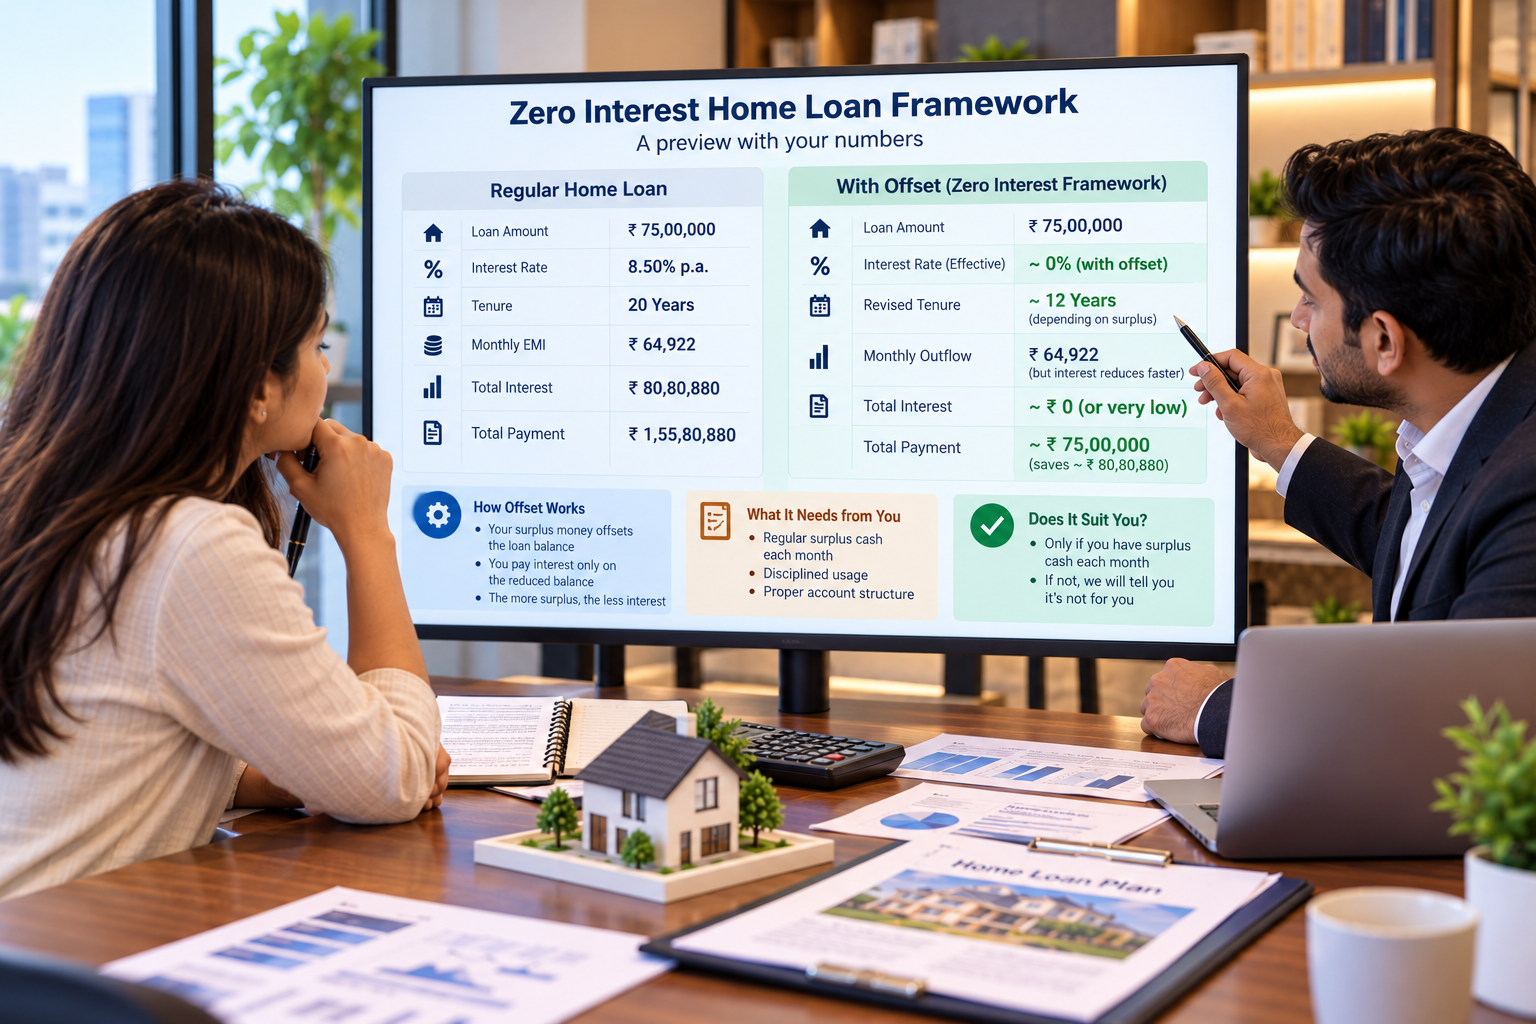
A preview of the Zero Interest Home Loan Framework, on your
numbers
How Offset works, what it needs from you, and crucially -
whether it suits your situation at all. If you do not have
surplus cash sitting idle each month, you will be told it is
not for you.
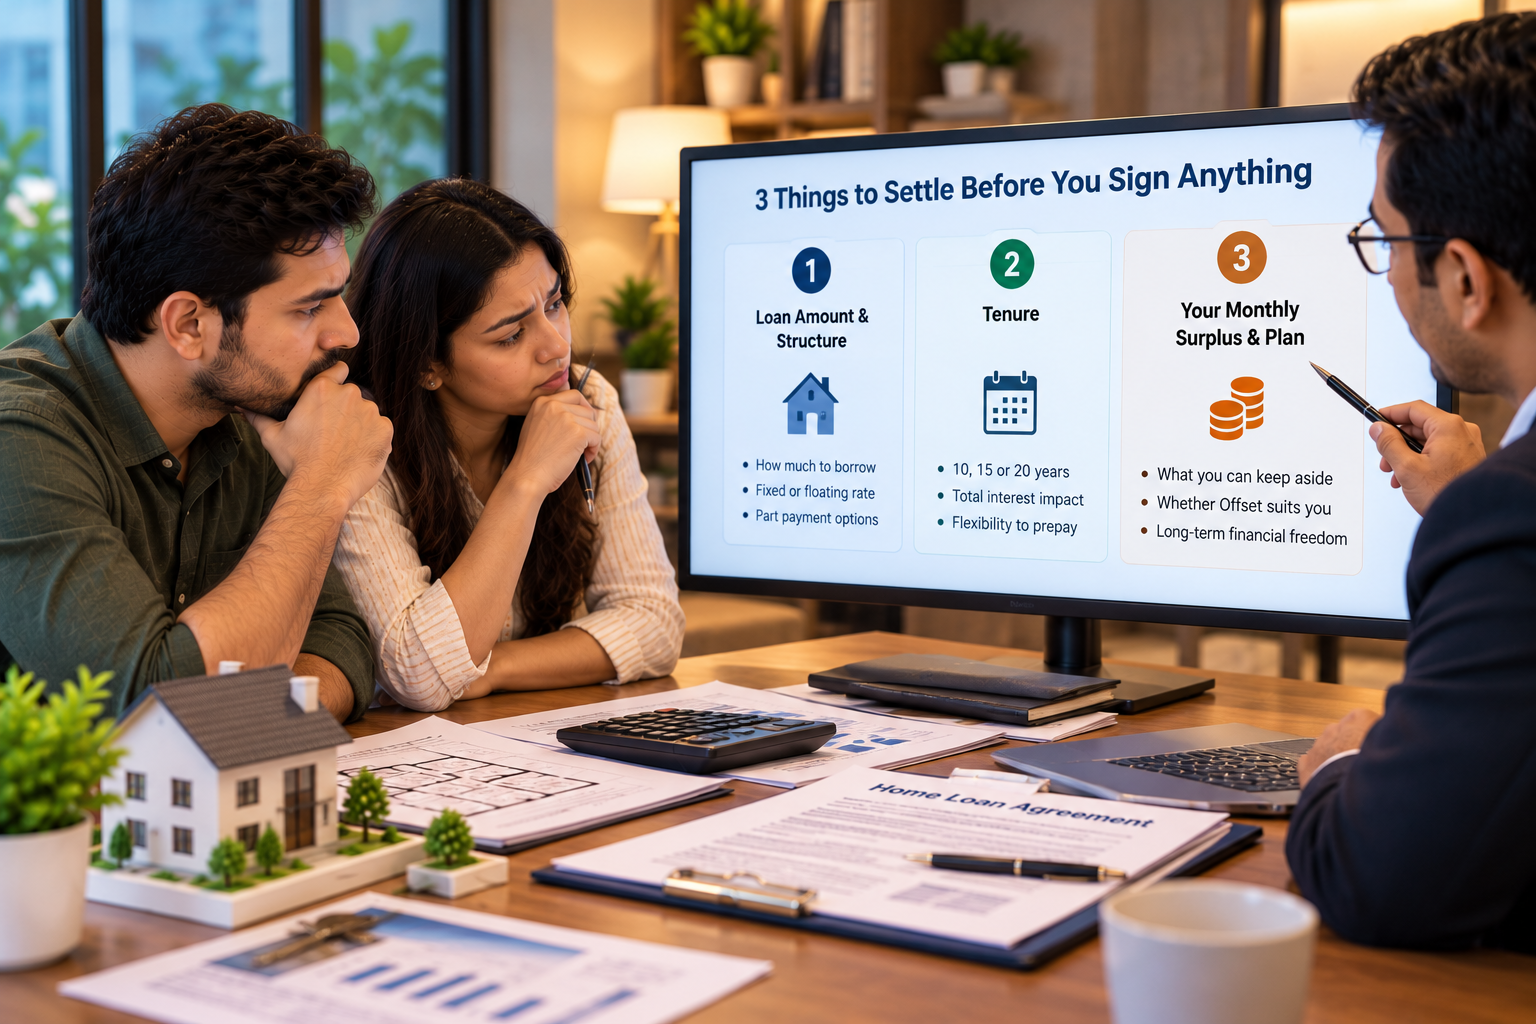
Three things to settle before you sign anything
Not twenty. Three. The ones that cannot be fixed afterwards.
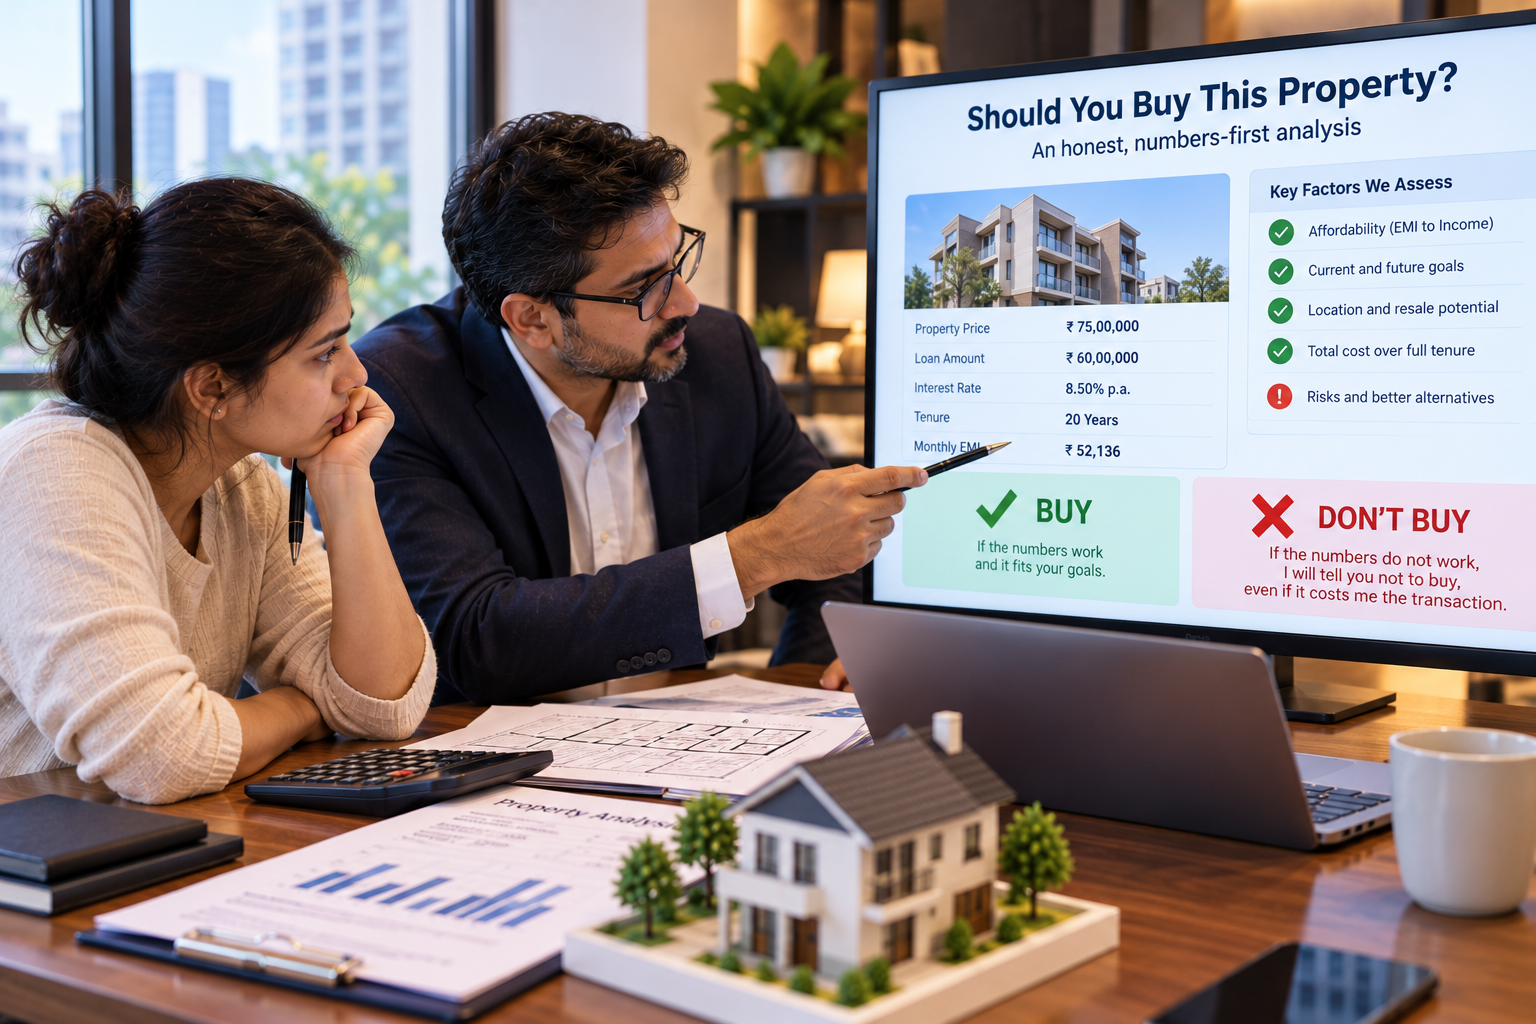
An honest read on whether you should be buying this property
at all
Including when the answer is no. "If the numbers do not work,
I will tell you not to buy, even if it costs me the
transaction." That is his sentence, not mine.
The first twenty minutes are entirely your numbers and nothing is
sold to you. In the last ten you are told the three steps - and if
there is a next step beyond that, it is named once and you are free
to ignore it.
What You Walk Away With Thirty Minutes From Now
A number you can say out loud at home
The real twenty-year cost of your loan, written down. You will
show it to your husband or wife that evening. Everybody does.
The end of the Excel sheet at eleven at night
Because the thing keeping you up was never a missing
calculation. It was not knowing whether anybody had checked
your thinking. Somebody will have.
A yes or no on whether that EMI is safe
Against your actual take-home, your actual commitments, your
actual cash flow. Not against what a lender decided you are
eligible for.
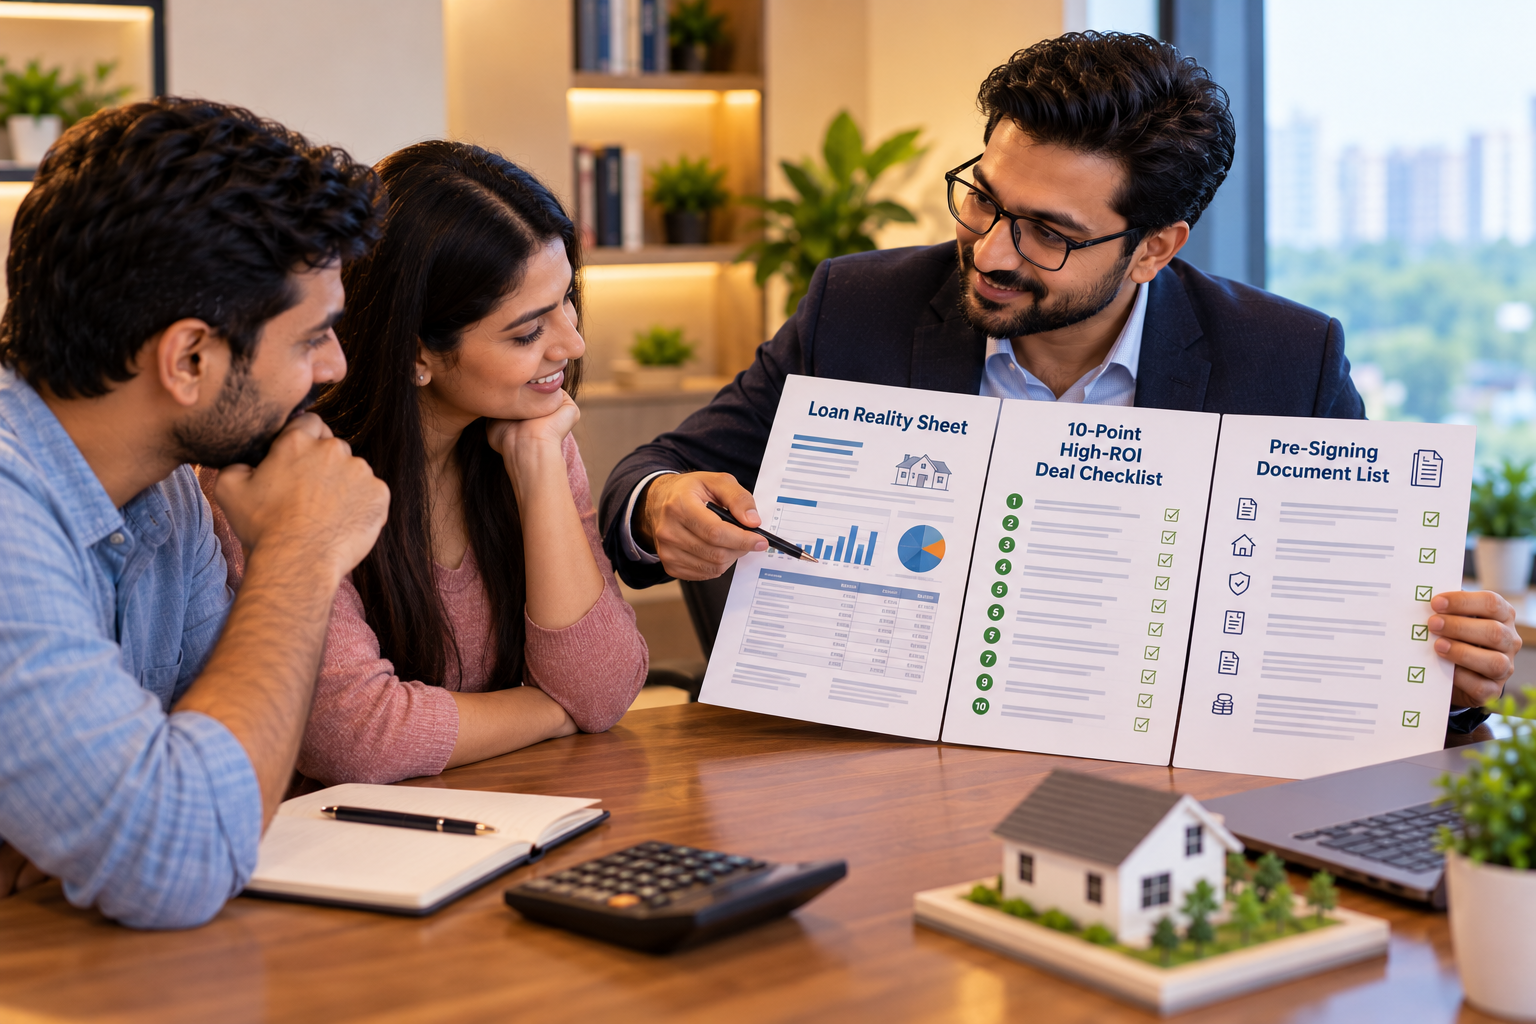
Three documents, yours to keep
Your Loan Reality Sheet with your own numbers written out, the
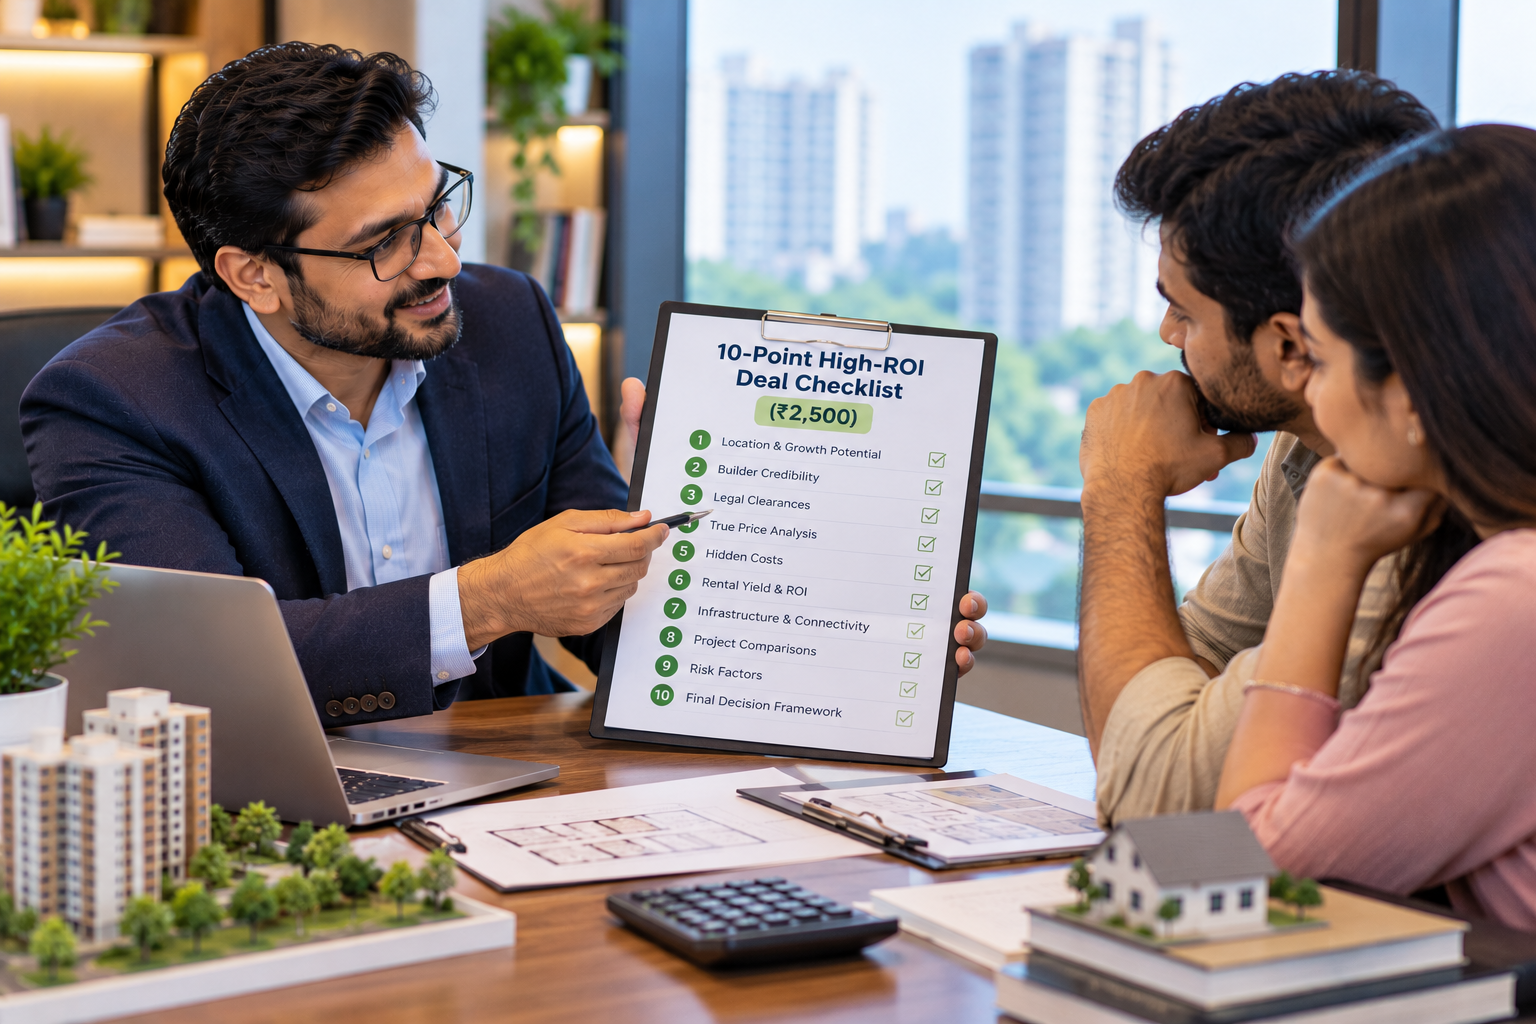
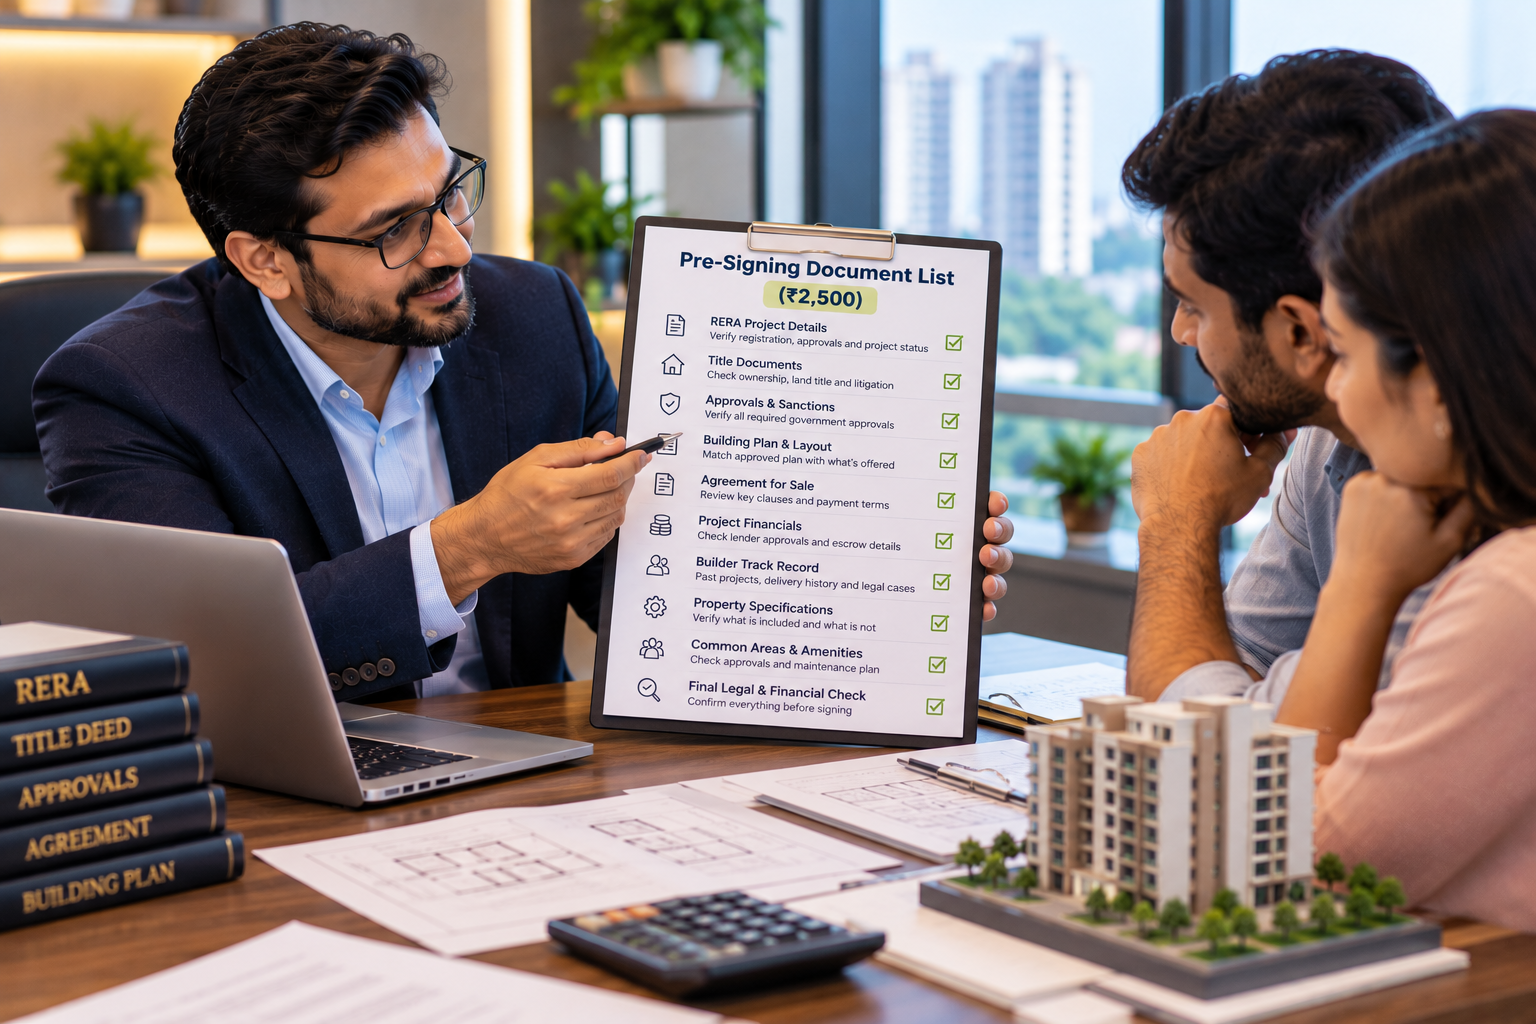
10-Point High-ROI Deal Checklist, and the Pre-Signing Document
List covering RERA, title and approvals. Yours even if you ask
for the ₹9 back.
One person who is not selling you anything
For the first time in three months. That alone is worth half
an hour, and several people have said exactly that at the end
of the call.
None of this requires you to commit to anything, change lenders, or
even buy a house. It requires thirty minutes and nine rupees,
against a decision you will carry until you are nearly sixty.
You will be paying this EMI until you are 58. Spend thirty minutes
finding out exactly what it costs before you promise it.
In property and home loan structuring, across Mumbai, Pune,
Thane and Navi Mumbai
Built on referrals
A ₹1 crore revenue practice built with no advertising at all,
until now
A registered company
Soaring RealFinTech Pvt Ltd - PropTech, FinTech and WealthTech
Every session, himself
10 to 12 a week, no team, no junior, no call centre
Eighteen years ago Vinod started watching people buy homes, and
after a few hundred of them he noticed something that has bothered
him ever since. People spend six months choosing between two
flats. They spend about six minutes choosing the loan.
The flat is the decision everybody talks about. The loan is the
one that costs them more - often more than the flat itself, as you
worked out on your own phone two screens ago. So he started doing
it the other way round: the loan first, the structure first, the
twenty-year number first, and the property only once those are
settled. That reordering is the whole of the Zero Interest Home
Loan Framework.
The practice has run for eighteen years entirely on referrals,
with no advertising of any kind. That is an uncomfortable thing to
say in an ad, and it is also the only proof that matters in this
business: people sent him their friends, their brothers and their
colleagues, which nobody does for an advisor who sold them the
wrong thing.
And here is something he says before you ask it. He may receive
compensation from a builder or a lender if a transaction
eventually happens. That is disclosed to you in writing before
anything. It is also exactly why he charges an advisory fee - so
that his advice is paid for by you, and is not dependent on you
buying.
❌ He will never tell you a bank is giving you a zero-rate loan.
No lender does. "Zero Interest" is the name of a framework, not
the name of a loan
❌ He will never guarantee you a saving, a tenure, a return or an
appreciation figure. If someone guarantees you a number on a home
loan, walk away from them
❌ He will not pretend his own framework suits everybody. If you
have no idle surplus each month, Offset will not help you, and he
will say so and move on
❌ He will not let you feel stupid for asking a basic question.
The fear of asking is what makes people sign things they do not
understand
❌ And he will not tell you to buy when the numbers say otherwise,
even when it costs him the transaction
What you get instead is half an hour with one person who has sat
through hundreds of these decisions, who has no inventory to clear
this quarter, and who has built an entire eighteen-year practice on
people trusting what he told them.
The thing he understood that changed everything
Everybody in this process optimises the interest rate, because the
rate is the only number anybody shows you. But the rate is one of
four things that decide what a loan actually costs. The other
three are the tenure you chose, the structure you were given, and
what your surplus cash does every single month while it sits in a
savings account earning almost nothing. Three of the four levers
are not controlled by the bank. They are controlled by you - and
nobody has ever told you they exist. That is why two people with
the same loan, the same rate and the same salary can end up paying
very different amounts over twenty years, and why the Reality
Check starts with arithmetic rather than with a product.
The Zero Interest Home Loan Framework.
The name describes the goal of the method, not a product. No lender
offers a zero-rate loan. The aim is to move your net interest cost
towards zero by structuring the loan, the tenure and your surplus.
Outcomes depend on your lender, rate, surplus and market conditions,
and are not guaranteed.
REALITY - you see the actual number
Nothing can be improved while it is invisible, and for most
people this number has been invisible for their entire adult
life.
✓ Total interest across the full tenure, on your own loan,
not an example
✓ The effective cost of the tenure you were advised to take
✓ Your EMI as a percentage of take-home, stress-tested
✓ The one slide most people photograph and send to their
spouse
Result: You stop negotiating in the dark. This step
happens on the ₹9 call.
STRUCTURE - how much you should borrow, not how much you can
The bank answered a question you never asked. This step
answers the real one.
✓ The right product and the right lender type for your
profile, not the fastest approval
✓ Tenure set deliberately, with the real cost of each extra
year on the table
✓ An OD-linked account where it genuinely fits, and only
where it fits
✓ The loan sized to your cash flow, then the property sized
to the loan - in that order
Result: The loan stops being whatever the first bank
offered you.
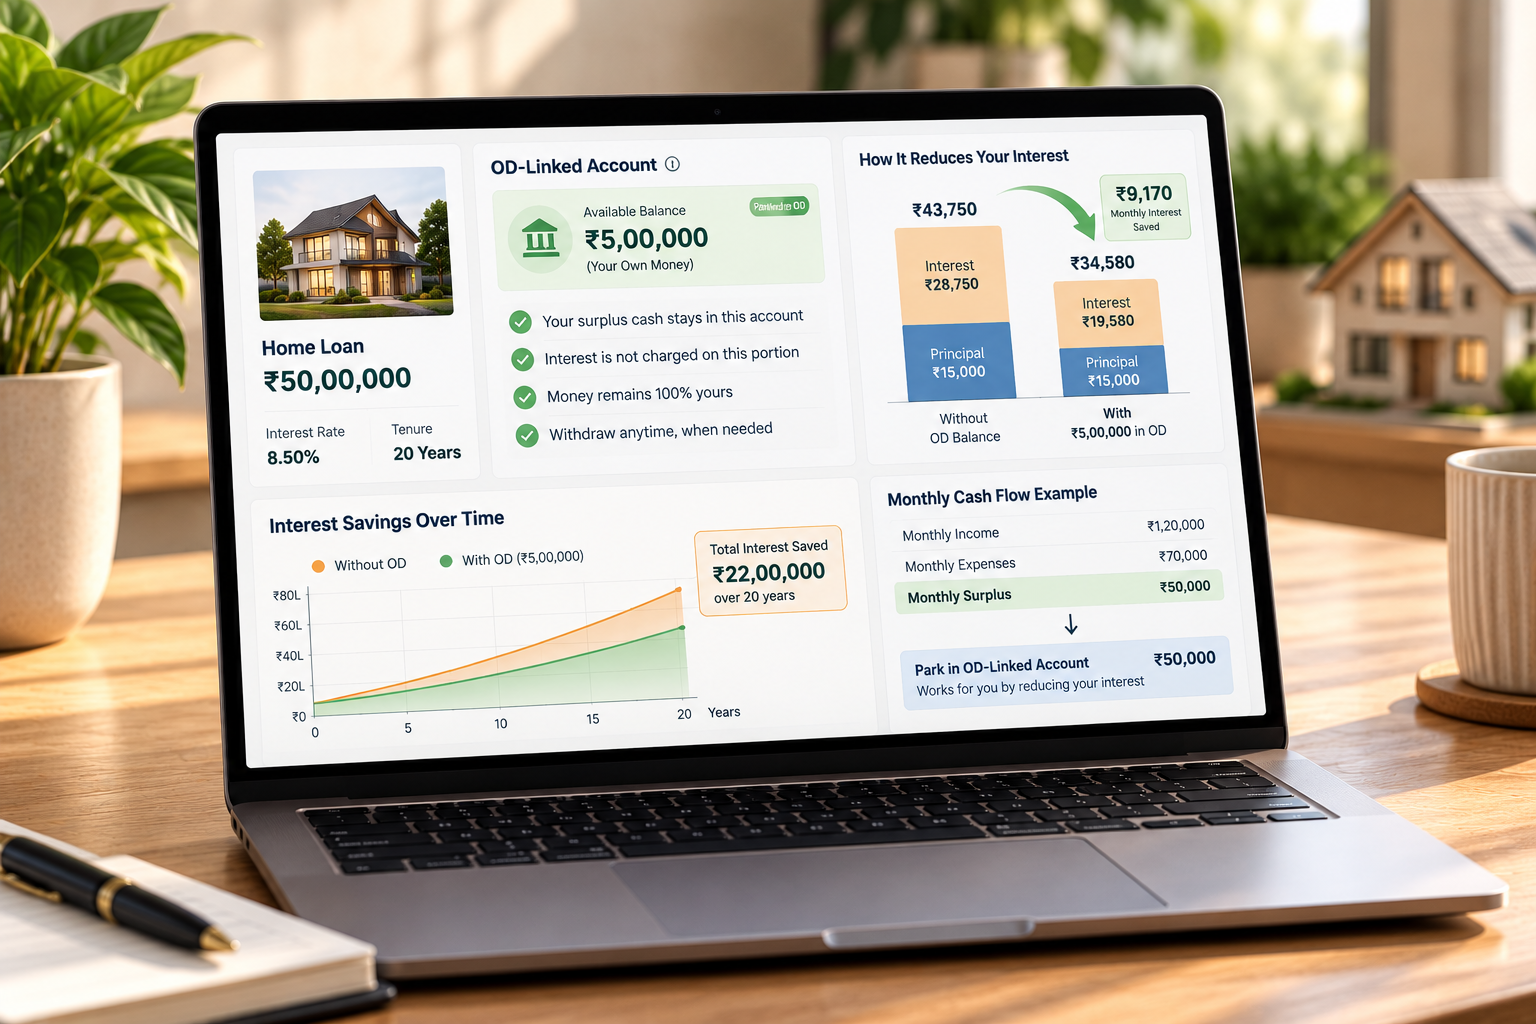
OFFSET - your idle cash stops being idle
This is the mechanical heart of the framework, and it is
deliberately explained in the open.
✓ Your surplus cash sits parked in the OD-linked account
instead of a savings account
✓ For every day it sits there, interest is not charged on
that portion
✓ The money stays entirely yours and you can withdraw it
whenever you want
✓ And if you do not have surplus sitting idle each month,
you will be told this step is not for you
Result: The same money does two jobs instead of sitting
still doing one badly.
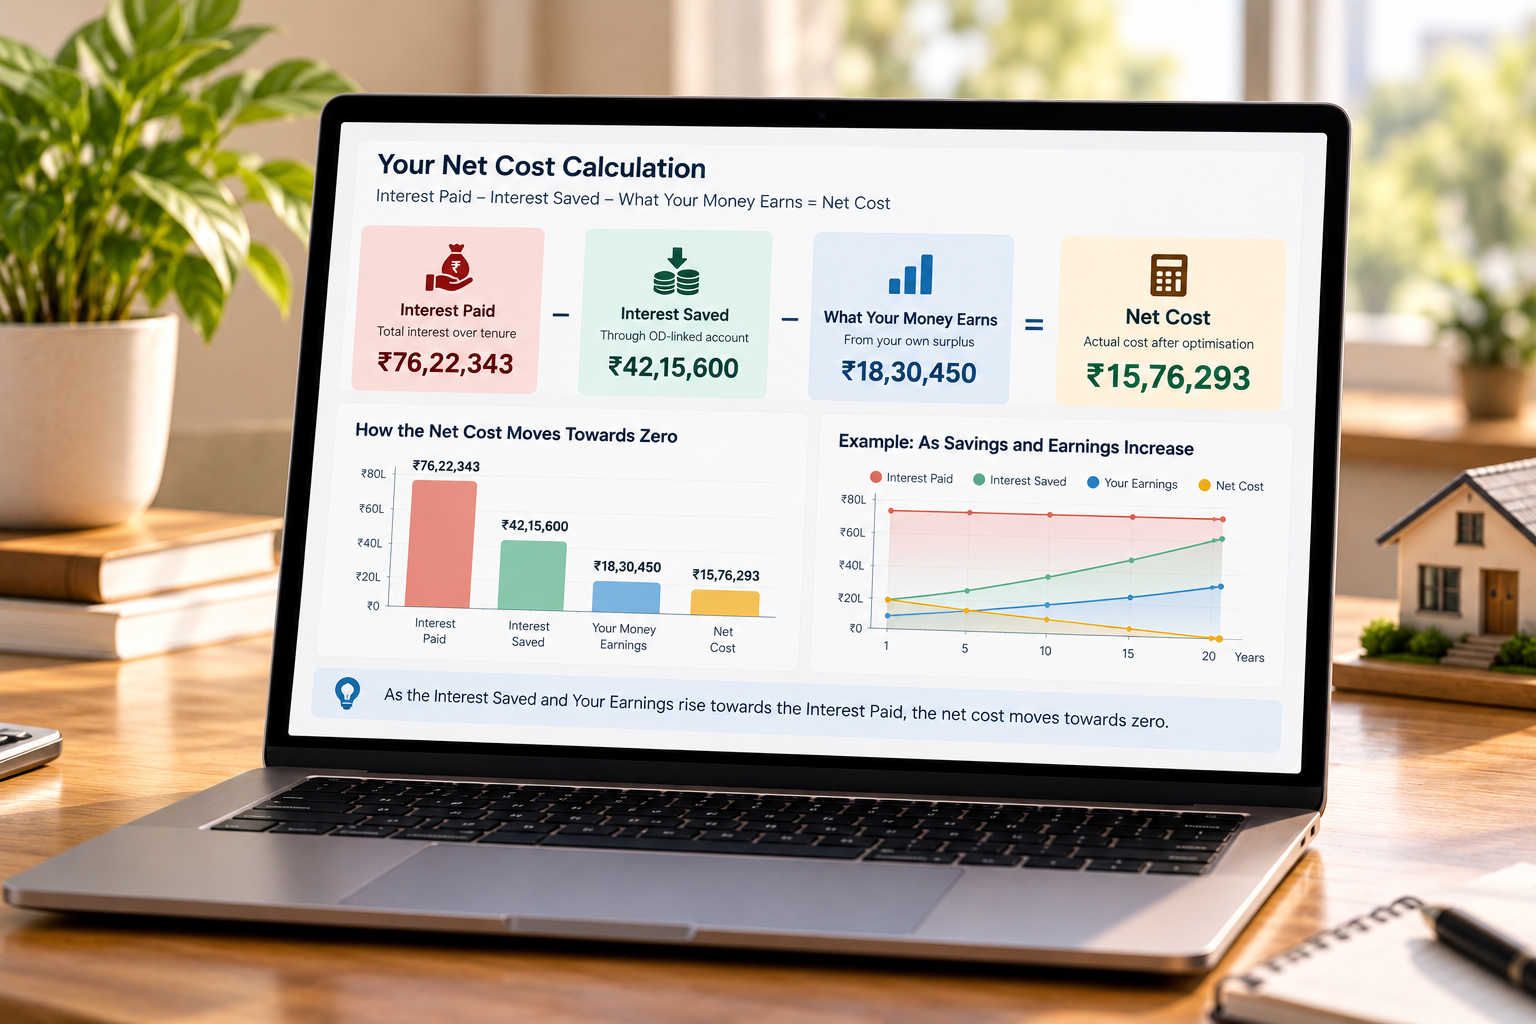
NEUTRALISE - the net cost moves towards zero
This is what the name actually refers to, stated plainly.
✓ Interest Paid, minus Interest Saved, minus what your own
money earns, equals your net cost
✓ The framework works on all three of those terms, not just
the first
✓ As the second and third rise towards the first, the net
moves towards zero
✓ Whether it reaches zero depends entirely on your lender,
rate, surplus and circumstances, and is never promised
Result: You are no longer optimising one number out of
four.
And for the thirty minutes themselves: if the session does not show
you at least one thing you did not know about your own loan, say so
and the ₹9 is refunded. You keep all three documents.
Interest Paid minus Interest Saved minus Money Earned equals your
net cost. Four levers, three of them in your hands, and nobody has
ever shown you any of them. That is the whole framework, and the
first lever gets pulled in thirty minutes.
Eighteen Years, Built Entirely On Referrals
There are no "I saved ₹42 lakh" testimonials on this page and there
never will be. In a financial category a savings figure in somebody
else's mouth becomes a claim in Vinod's, and this page does not make
claims.
Eighteen years, no advertising
The practice has run entirely on referrals - friends, brothers
and colleagues sent to him by people he advised.
A registered company
Soaring RealFinTech Pvt Ltd - PropTech, FinTech and
WealthTech, operating as FinProRealtors.
Arithmetic you can check
Watch him do the arithmetic for sixty seconds. If it is wrong,
you will know immediately, because it is only multiplication.
There are ten to twelve of these sessions a week. Vinod takes every single one of them himself.
No team, no junior advisor, no call centre reading from a script.
Ten to twelve is what one man can do properly alongside the
clients he already has. When the week is full, the next slot is
the following week - and property decisions do not wait politely.
Which is also why it is ₹9 and not free. Free sessions no-show at
sixty to seventy percent, and every no-show is half an hour taken
from somebody who was serious. ₹9 is less than a vada pav. It is
not a fee, it is you opening UPI and entering a PIN, which is the
smallest possible proof that you intend to turn up.
Pick a slot, pay the ₹9, and answer four short questions on WhatsApp
- your property budget, your loan amount, your tenure, and when you
need to decide. The session then starts with your numbers instead of
with introductions.
A private 30-minute 1:1 Zoom session with Vinod himself
Not a team member, not a sales call, and the only one-to-one
entry point he offers.
Your Real Number
The total interest on your own loan across the full tenure,
calculated live, in front of you.
Your EMI-to-income stress test
Whether that EMI is genuinely safe against your take-home for
twenty years.
Your Loan Reality Sheet
Your own numbers, written out, so you can show your spouse and
your CA rather than trying to repeat them from memory.
The 10-Point High-ROI Deal Checklist (₹2,500)
How to read past a brochure.
The Pre-Signing Document List (₹2,500)
Exactly what to verify on RERA, title and approvals before you
sign anything.
And if the session does not show you at least one thing you did not
know about your own loan, the ₹9 comes back and you keep all three
documents.
The three documents are yours whatever happens next. Whether you
work with him, whether you buy, whether you ask for the refund.
Which means the worst possible outcome of this page is that you
spend nine rupees, learn your own twenty-year number, get the nine
rupees back, and keep ₹5,000 of checklists.
Add it up
The 10-Point High-ROI Deal Checklist - ₹2,500
The Pre-Signing Document List - ₹2,500
Your Loan Reality Sheet, personally prepared
The 30-minute 1:1 session with Vinod
Documents alone: ₹5,000Your price today: ₹9
And the ₹9 is refundable. The ₹5,000 is not - it is yours
regardless.
₹9 · 30 minutes · 1:1 on Zoom · All three documents kept regardless
Here is the arithmetic one last time. You are about to commit to a
payment every month until you are nearly sixty, on a loan whose
total cost you have never seen. This costs nine rupees and half an
hour. If it teaches you nothing, the nine rupees comes back and you
keep ₹5,000 of checklists. There is no version of this where you
lose money. There is only the version where you sign on a Saturday,
and work out the real number in your car afterwards.